
1ndex Strategy Index Weekly | 2-8 November 2026
Directional led the 1ndex strategy indices in the week of 2–8 November 2026, returning +1.17%. Delta Neutral gained +0.35%, while Market Neutral was effectively flat. The spread between the best and worst index was 1.17 percentage points.
Weekly index performance
| Index | 2–8 Nov | 2026 YTD |
|---|---|---|
| Delta Neutral | +0.35%+17.96% ann. | +10.52%+12.07% ann. |
| Market Neutral | −0.00%−0.04% ann. | +10.89%+12.49% ann. |
| Directional | +1.17%+61.01% ann. | +17.90%+20.55% ann. |
Market Neutral’s slightly negative weekly return rounds to zero. Weekly annualised figures multiply the unrounded weekly return by 52 and are for comparison only.
Delta Neutral
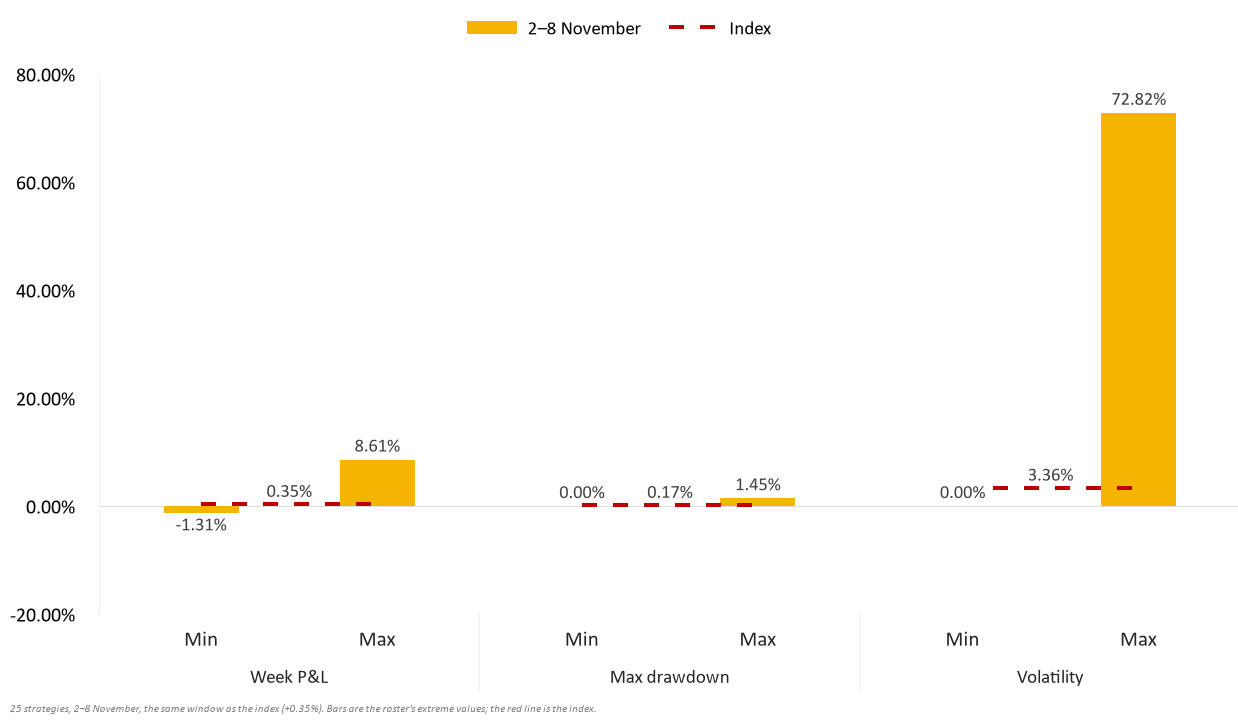
The index rose 0.35%, with four positive sessions and three negative sessions. It ended 0.05% below its inception high. Annualised volatility was 3.36% and maximum intraweek drawdown was 0.17%. Component returns ranged from −1.31% to +8.61%, and the largest component drawdown was 1.45%.
Market Neutral
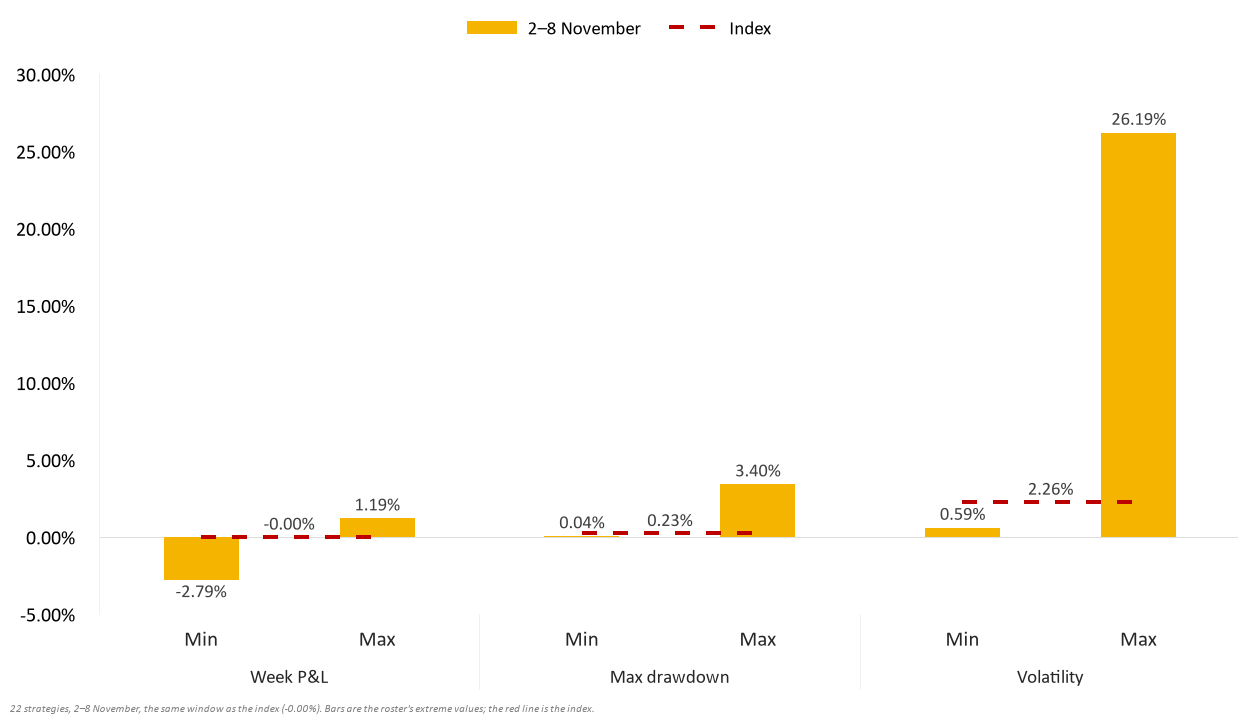
The index finished effectively flat, with four positive sessions and three negative sessions. It was 0.81% below its 11 October high. Its annualised volatility of 2.26% was the lowest of the three indices. Component returns ranged from −2.79% to +1.19%, the narrowest range of the three groups. The largest component drawdown was 3.40% and the highest annualised component volatility was 26.19%.
Directional
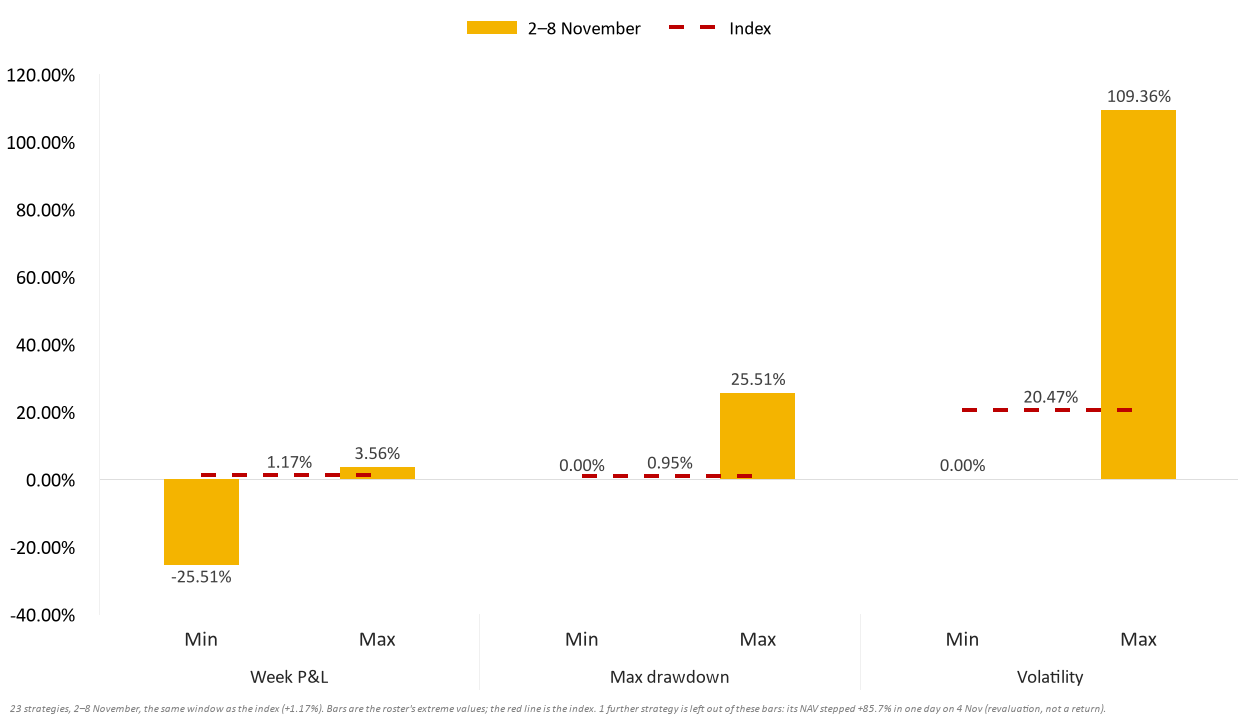
The index gained 1.17%, with its largest positive session driving the weekly result. Annualised volatility reached 20.47% and maximum intraweek drawdown was 0.95%. The index was 2.39% below its 22 September high. Component returns ranged from −25.51% to +3.56%, with annualised volatility reaching 109.36% at the high end. The component chart excludes one strategy affected by a NAV revaluation.
Year to date
Directional remained ahead at +17.90%, followed by Market Neutral at +10.89% and Delta Neutral at +10.52%. In the prior week, Delta Neutral returned −0.11%, Market Neutral +0.33% and Directional −0.28%. Daily return correlation was 0.56 between the two neutral indices, 0.21 between Directional and Delta Neutral, and 0.12 between Directional and Market Neutral.
Method
Each index is an equal-weighted composite of listed strategies in its category, rebased to 1.000 at the start of the window. Index returns are shown before fees and financing, with no risk-free rate adjustment. Volatility is the standard deviation of daily returns annualised using 365 days. Drawdown measures the decline from peak to trough within the stated window. Component charts compare the lowest and highest constituent readings with the corresponding index figure.
Explore strategy performance, risk metrics and team profiles on 1ndex.
Comments ()