
Crypto Quant Strategy Index XV August & September 2026
Executive Summary
This report draws on data from the 1ndex platform to benchmark the performance of Delta Neutral, Market Neutral and Directional strategies in August and September 2026. Complementing these benchmarks, granular data provided in collaboration with participating crypto trading teams offers deeper insight into trading activity, return composition and coin-level exposure.
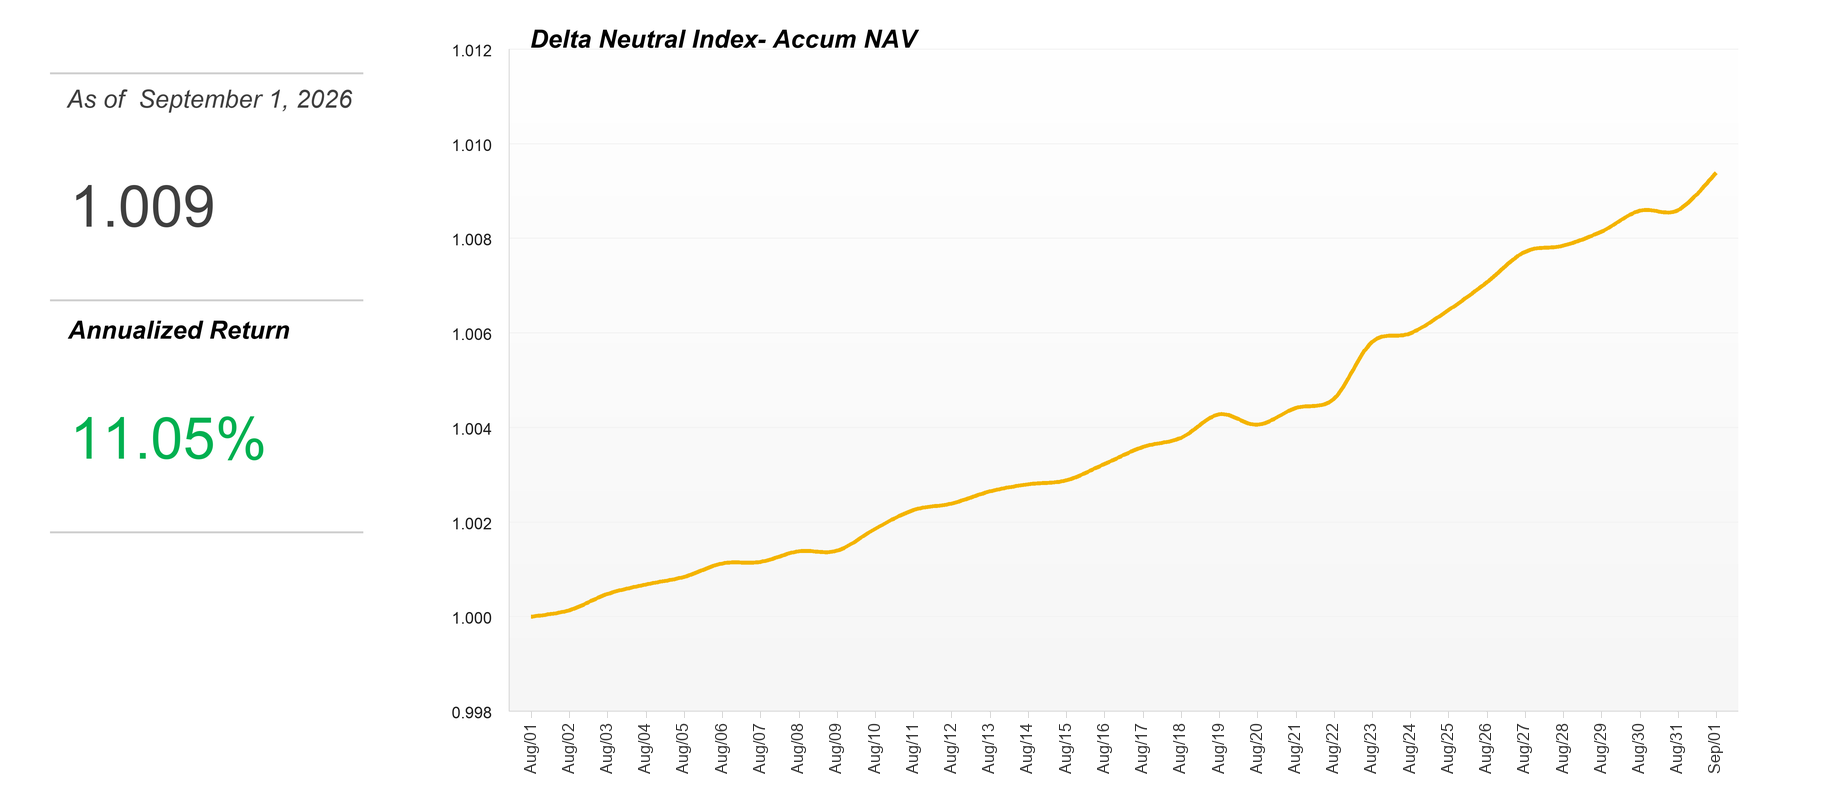
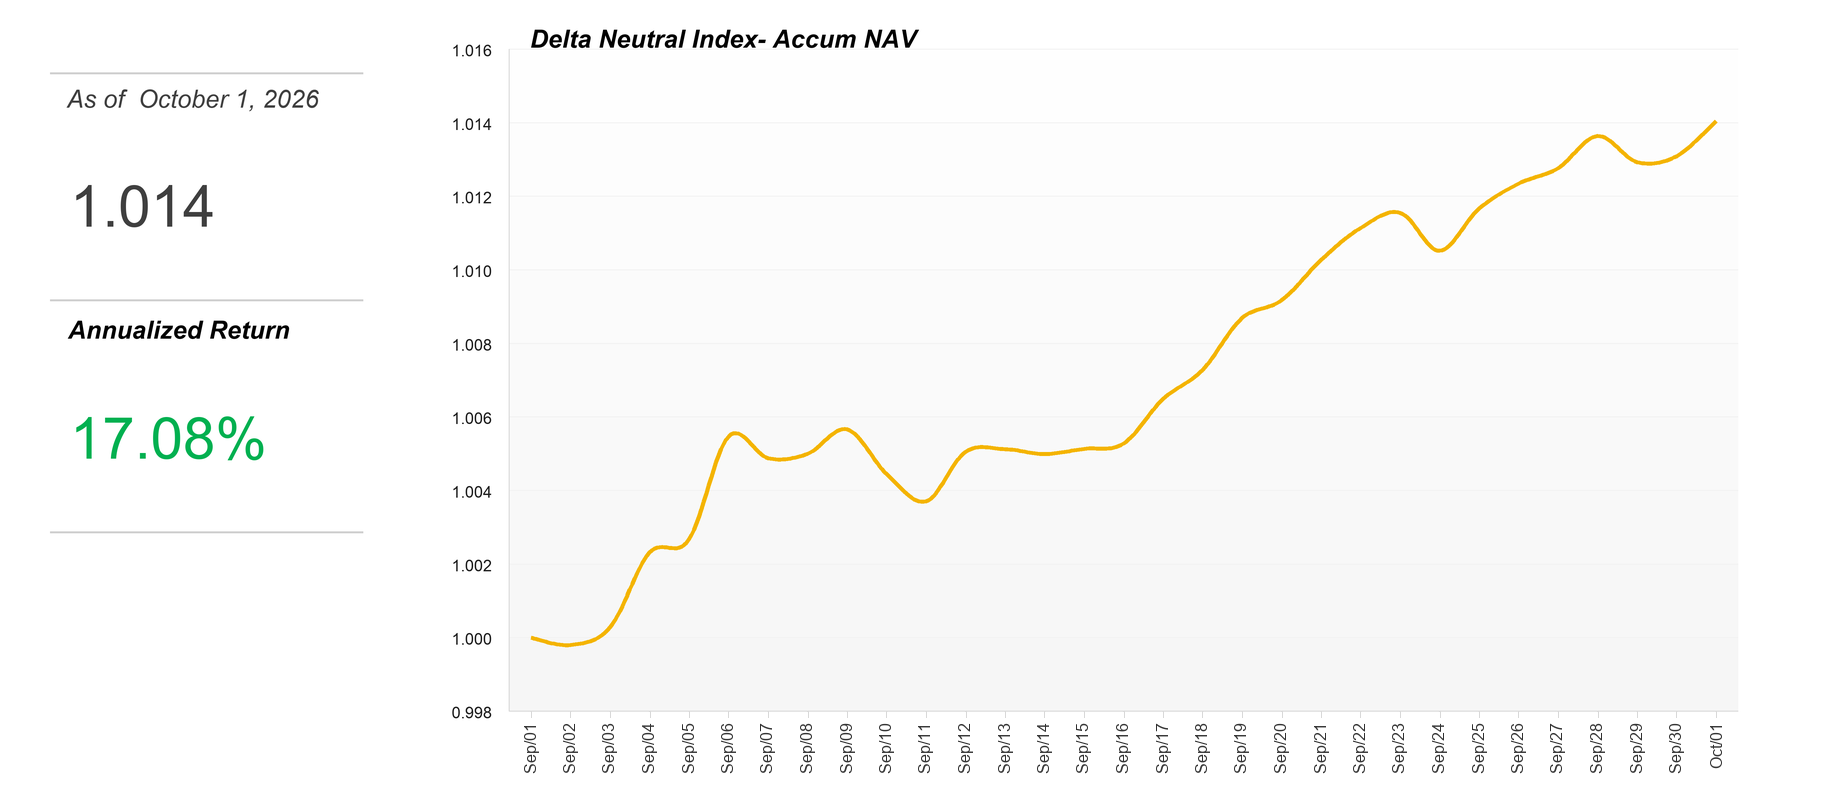
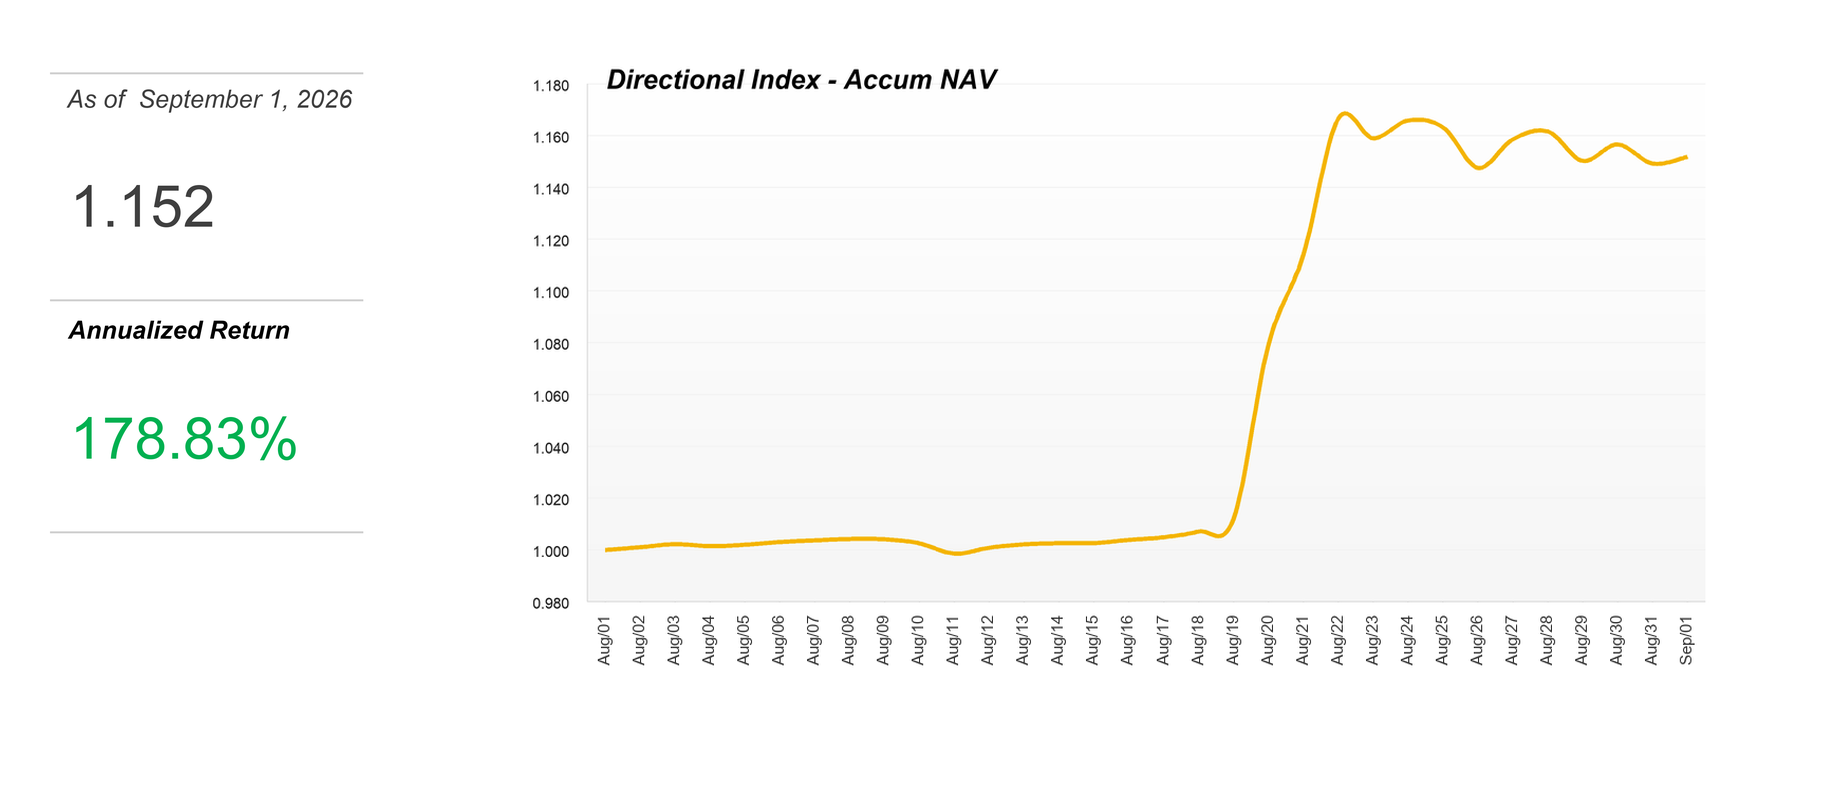
Directional strategies led performance in August, with the index gaining 15.19%, before moderating to 1.45% in September. Delta Neutral delivered positive returns in both months, improving from 0.94% to 1.40%, while Market Neutral posted more modest gains of 0.50% and 0.18%, respectively. The results highlight a marked shift in relative performance: Directional’s substantial August lead narrowed sharply in September, when its monthly return was broadly in line with Delta Neutral.
Parameters
- Quote Source: CoinMarketCap (CMC)
- Granularity: Daily
- Index start time: August 1 and September 1, 2026, respectively, at 00:00 UTC
- Cut-off Time: 00:00 UTC
- Sample Exchange Distribution: Binance, OKX, Bybit, Gate, LTP Rapidx, etc
- Accum. NAV: Time-Weighted Return (TWR)
- Risk-free rate: 4.3%
(based on avg data of US 10-Y Treasury Yield in 2025) - Daily Minimum Acceptable Return (MAR): 0
Note: Exchange selection may affect reported performance because fee structures, commissions, execution conditions, and slippage differ across venues. The index does not adjust for these venue-specific differences, which should therefore be considered when comparing results.
Calculation method
The Delta Neutral index is based on data from the 1ndex platform, with NAV rebased to 1.000 at the start of each monthly reporting period to facilitate performance comparisons. Index-level performance and constituent observations provide the basis for the return and risk analysis, while detailed trading team data offers additional insight into strategy execution, return composition and coin-level exposure. The two datasets are complementary and may differ in sample coverage.
2026-08 | delta neutral index
2026-09 | delta neutral index
Note: We use the arithmetic mean instead of the weighted average because the current sample size is relatively small, and the weights in a weighted average cannot accurately reflect the actual weights of the trading team. Therefore, the impact of principal has been normalized.
Indicators
Profit and Loss (PNL) and Risk
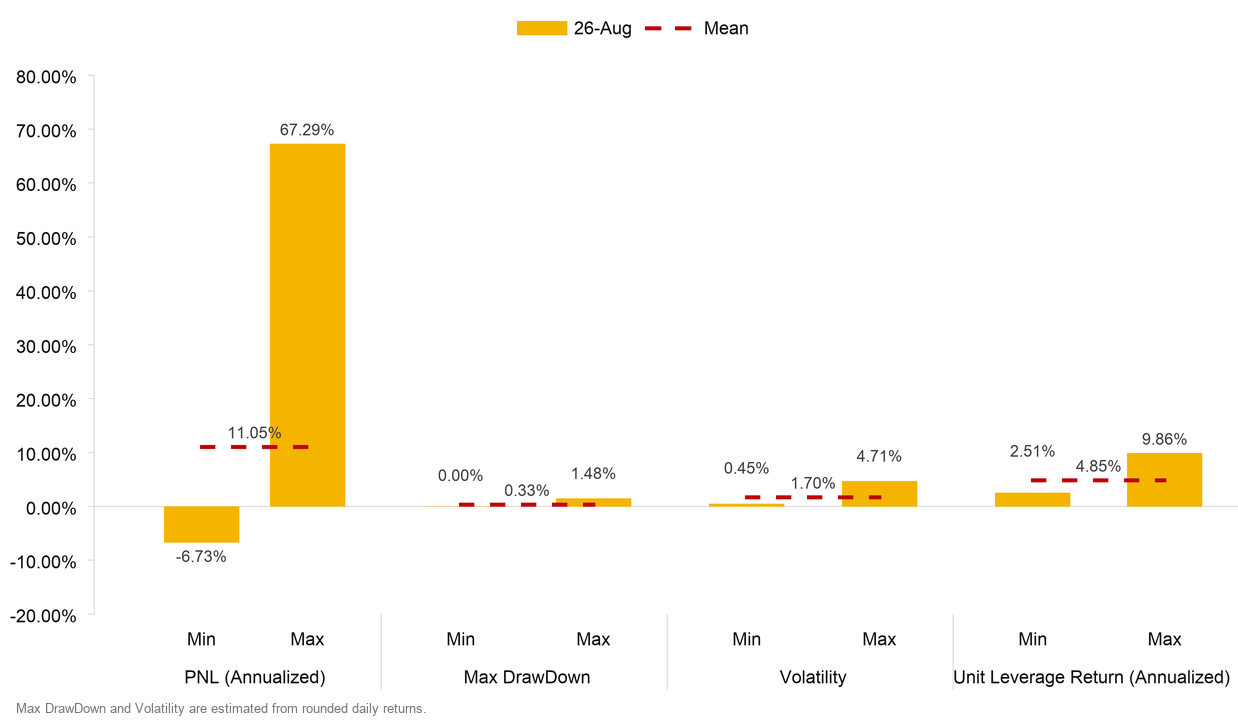
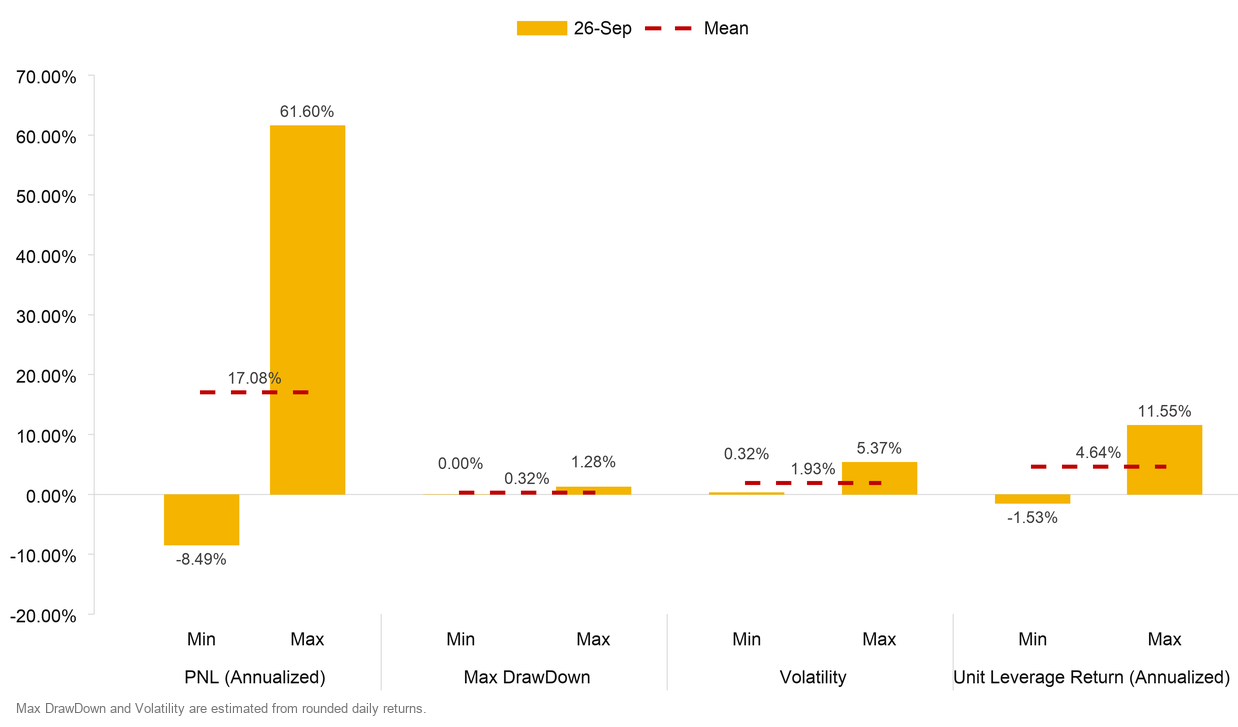
Delta Neutral mean annualized return was 11.05% in August and 17.08% in September. Estimated mean maximum drawdown was 0.33% in August and 0.32% in September.
2026-08 | PNL and risk | delta neutral
2026-09 | PNL and risk | delta neutral
Note: see Index formula for full methodology and calculations.
Strategy Features
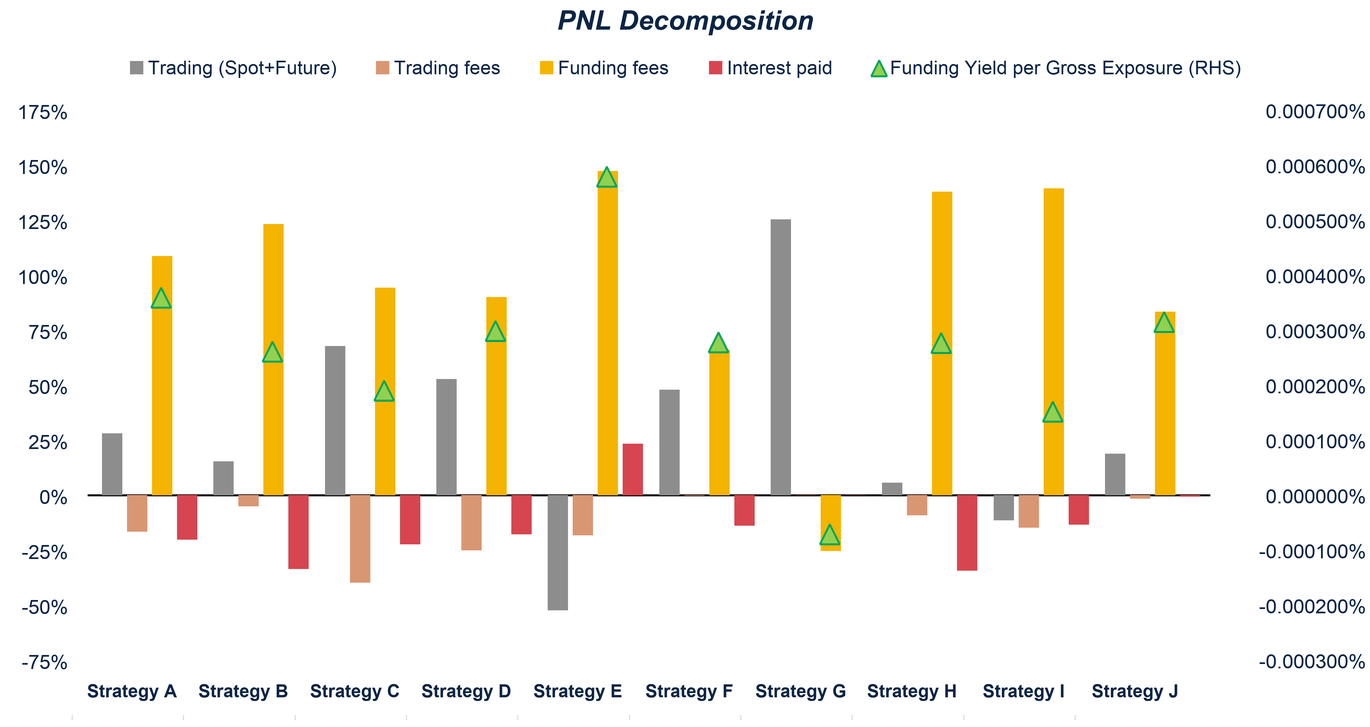
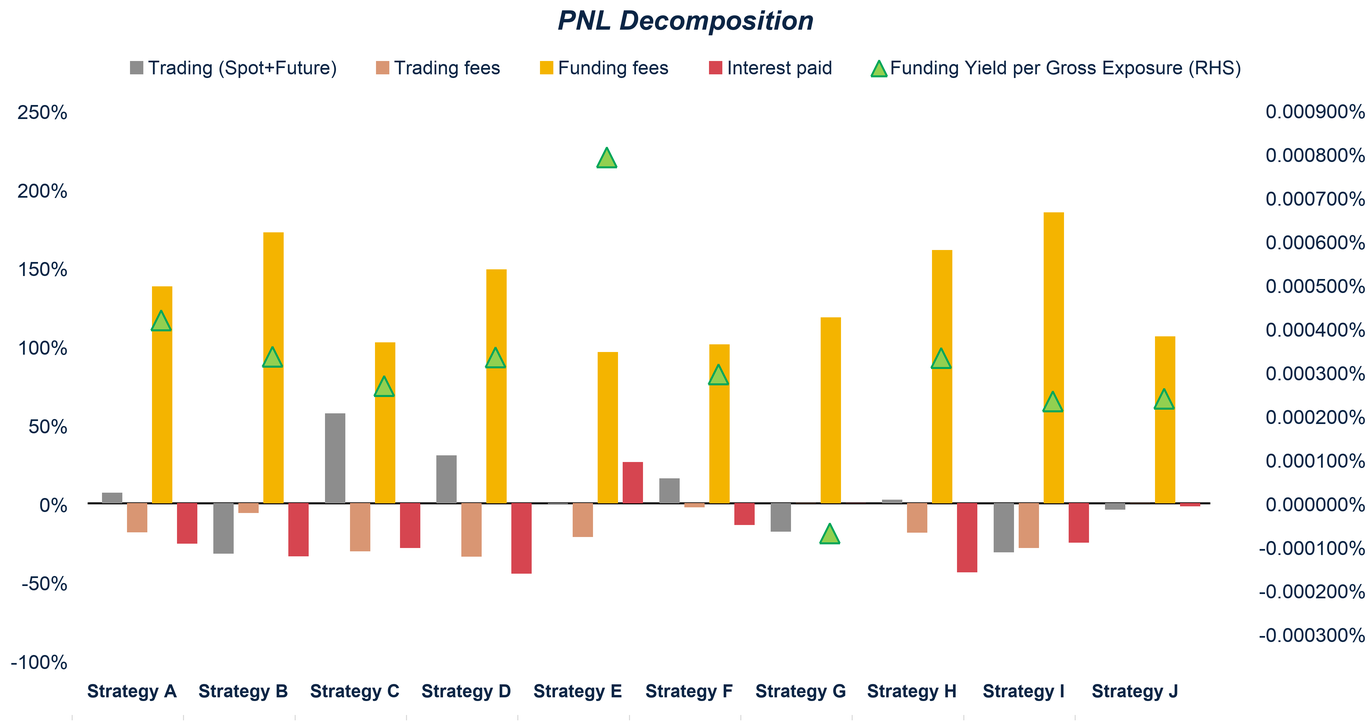
Within the broader Delta Neutral universe, this section focuses specifically on funding arbitrage strategies, where funding income is a key driver of returns. Using execution records provided by participating trading teams for August and September 2026, we decompose P&L into funding income, trading P&L, trading fees and interest paid to assess the contribution of funding capture to overall performance.
To evaluate funding capture efficiency within this subset, we use Funding Yield per Gross Exposure (FYpGE), defined as funding income generated per unit of gross exposure. Higher FYpGE indicates greater funding income capture relative to exposure deployed.
2026-08 | PNL decomposition | delta neutral
2026-09 | PNL decomposition | delta neutral
Note:
-
The PNL Decomposition is calculated using various records to generate detailed PNL data, breaking down portfolio performance into individual components.
-
See Index formula for full methodology and calculations.
Coin Distributions
We aggregated daily position snapshots provided by participating trading teams over two monthly reporting periods: August 1 to September 1 and September 1 to October 1, 2026, with each period measured at a 00:00 UTC cut-off. Absolute USD exposure was consolidated by underlying asset to assess the allocation between CMC top-20 assets and other coins, as well as the concentration and diversification of each strategy’s coin exposure.
Overall, small-cap coins accounted for a higher proportion of gross exposure than large-cap coins (CMC top 20) in both August and September. Among large-cap coins, BTC and SOL represented the largest exposure shares in our sample of participating teams.
2026-08 | Coin distribution | delta neutral
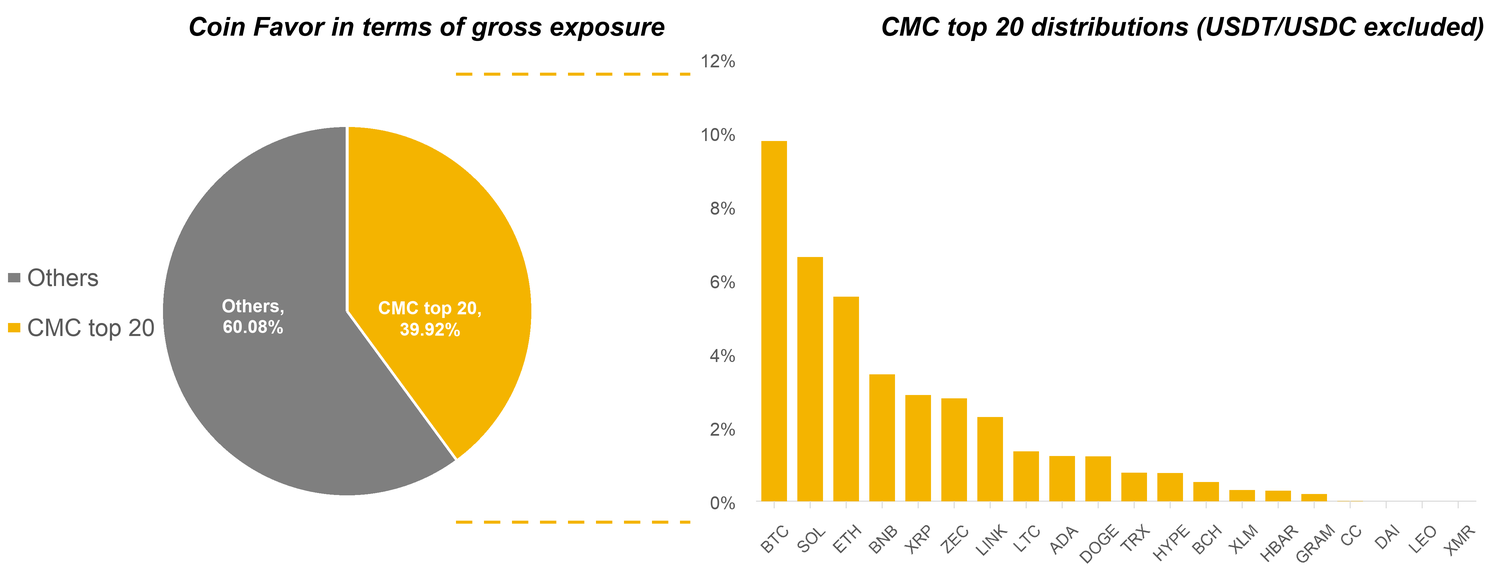
2026-09 | Coin distribution | delta neutral
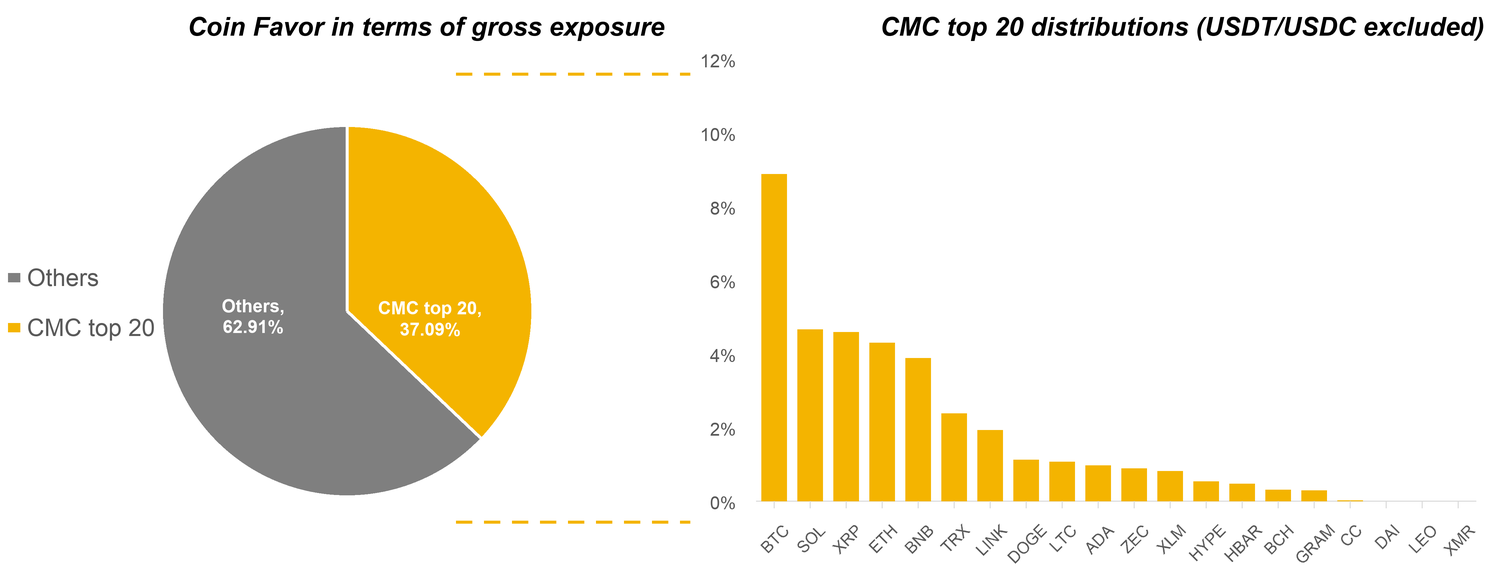
2026-08 | Coin favor by team | delta neutral
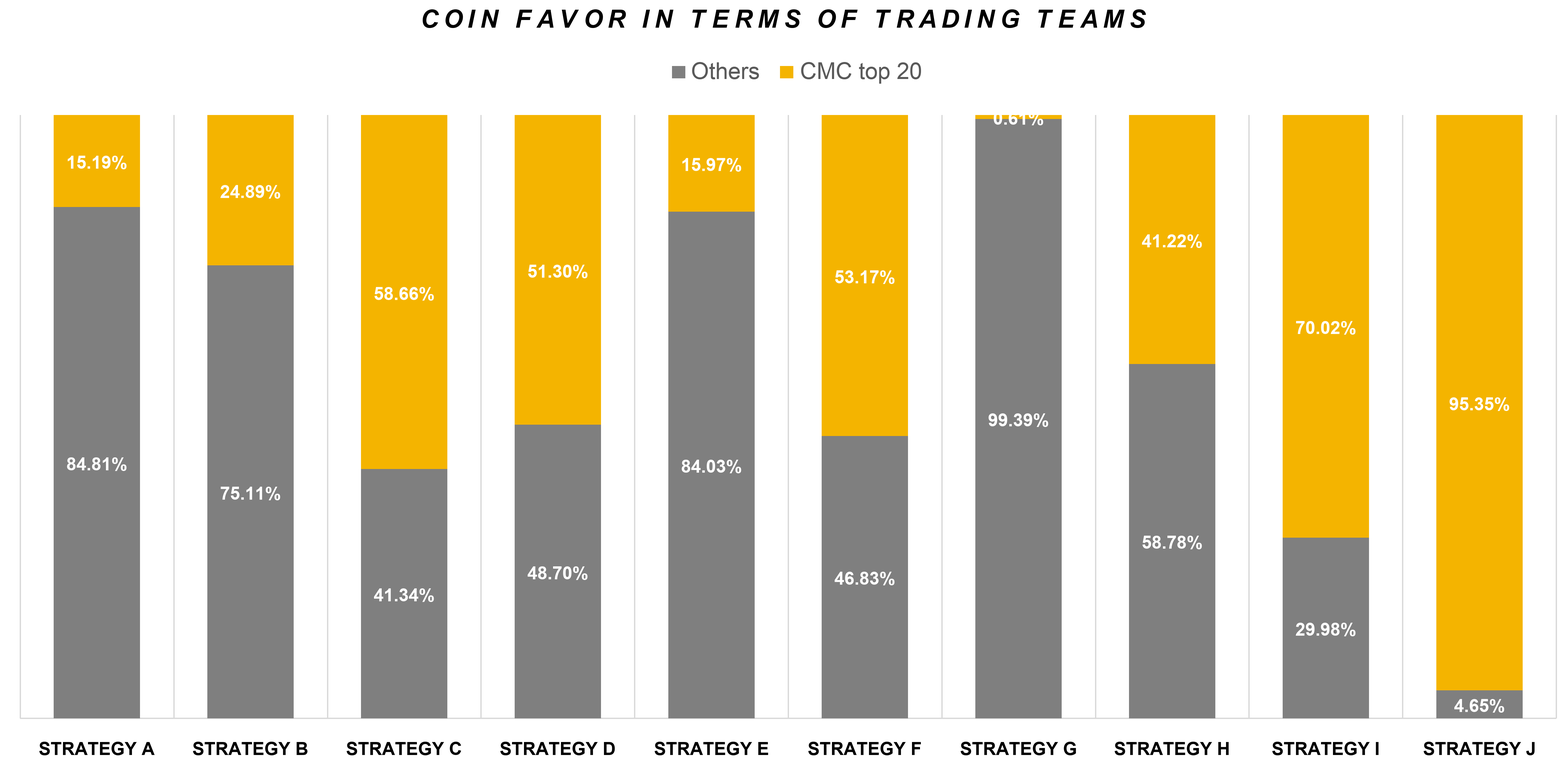
2026-09 | Coin favor by team | delta neutral
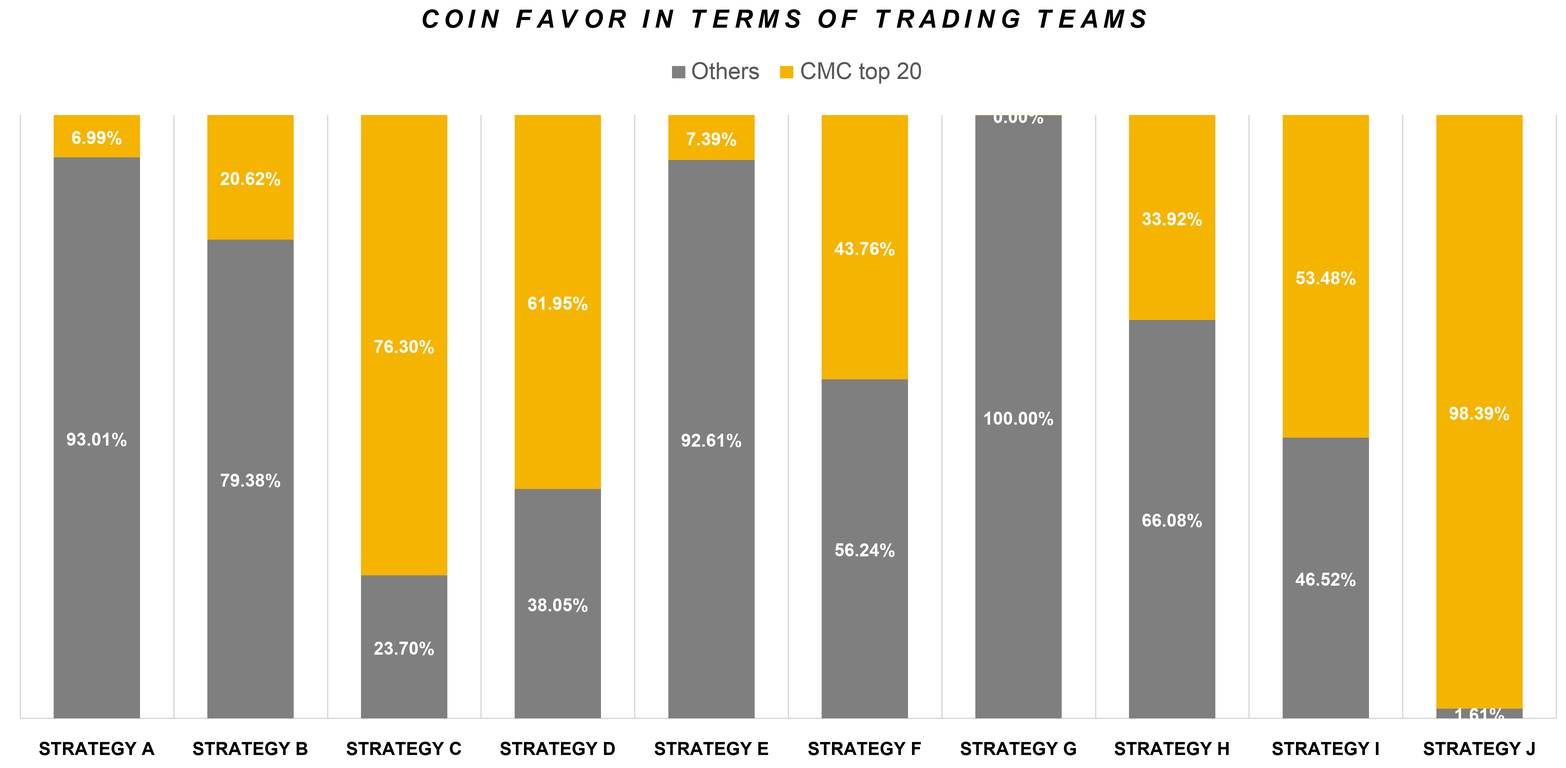
2026-08 | CMC top-20 exposure by team | delta neutral
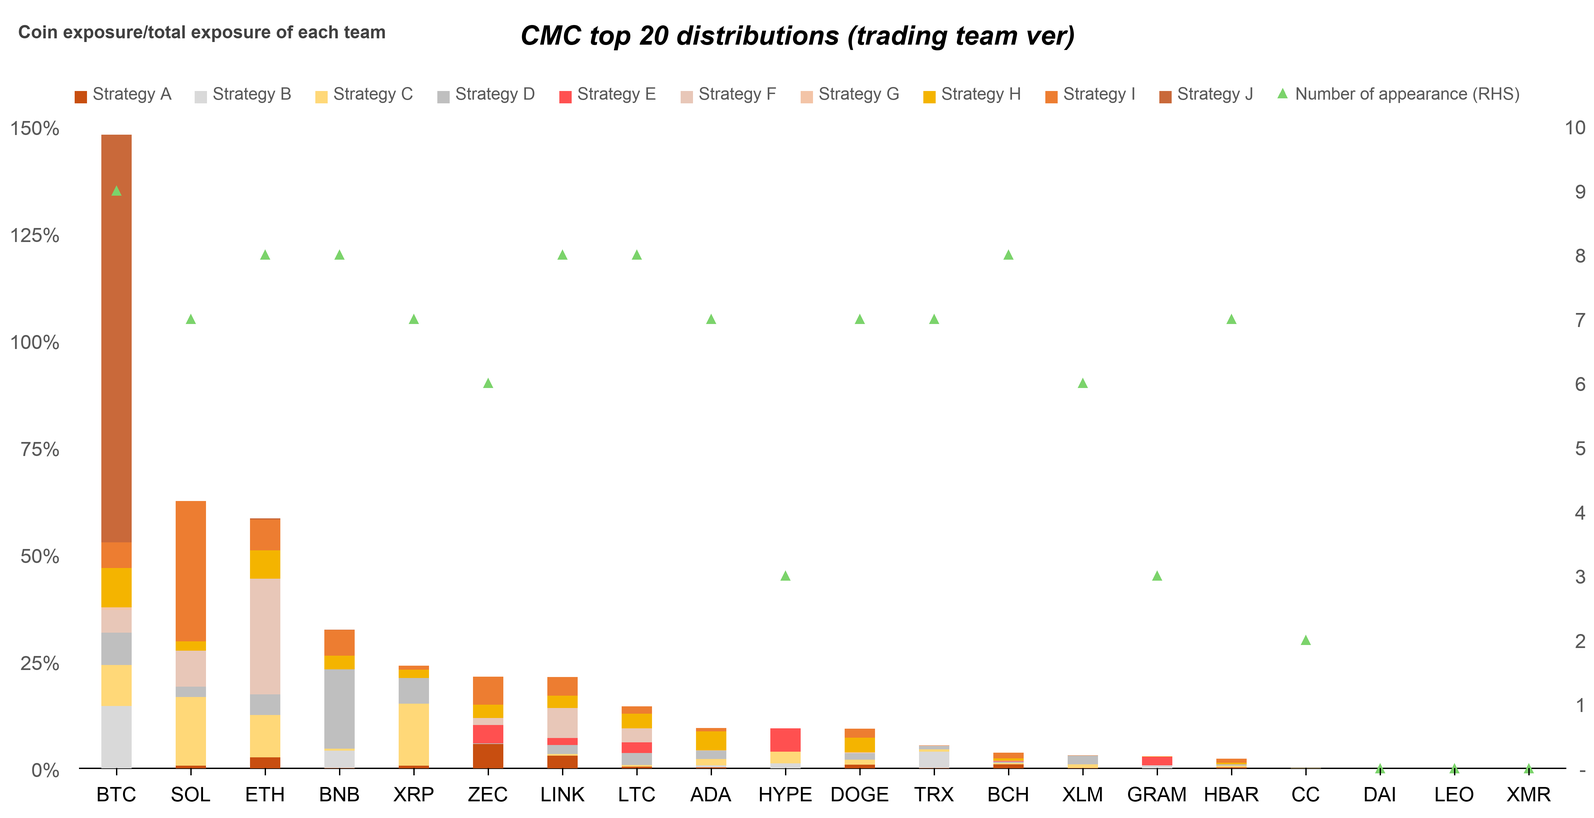
2026-09 | CMC top-20 exposure by team | delta neutral
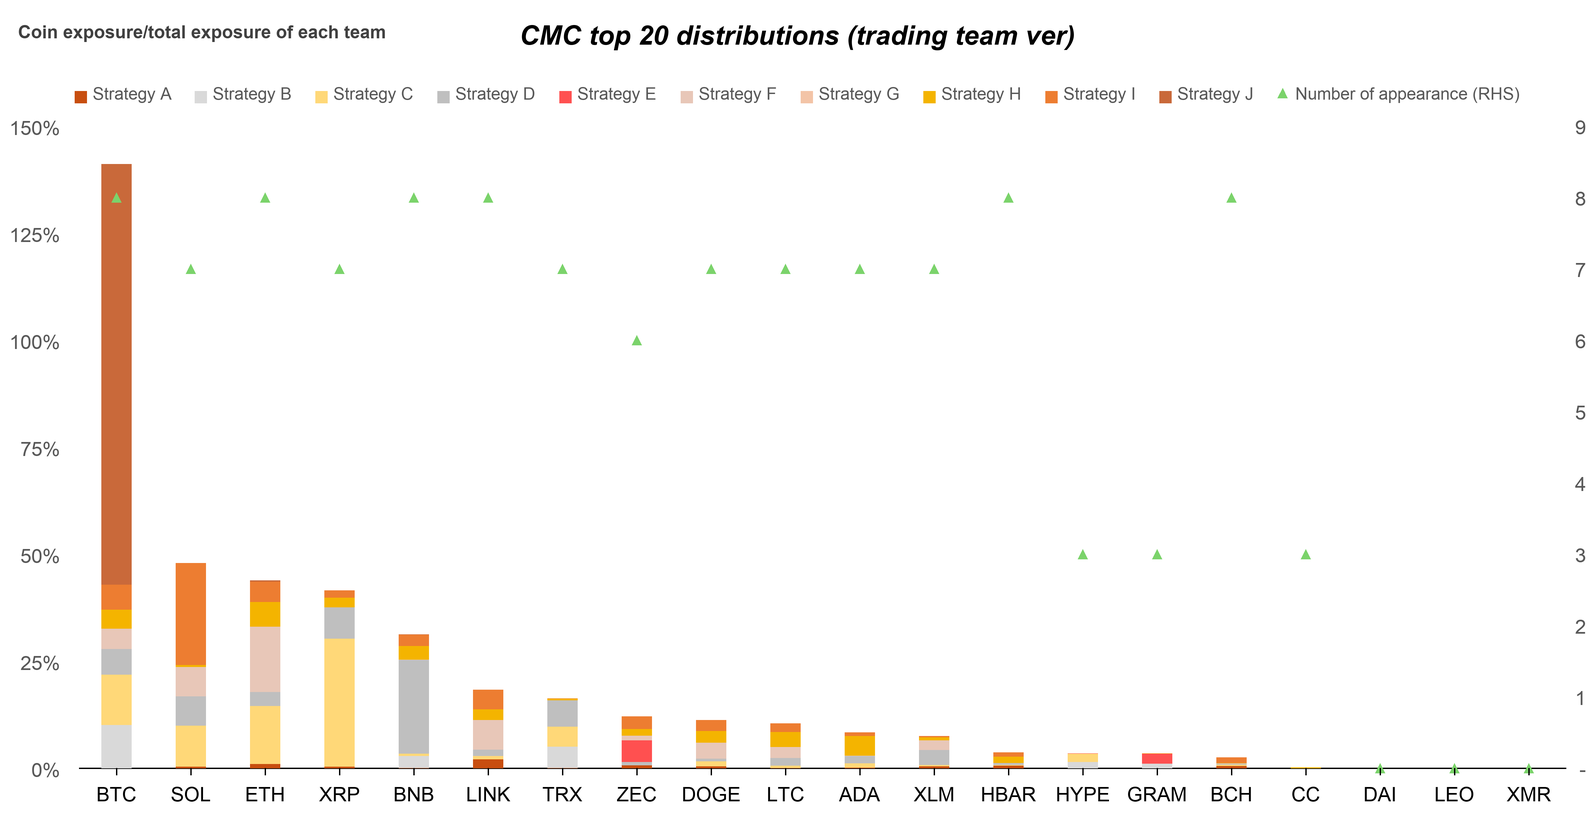
Note:
-
USD exposure = Delta * Underlying Price
-
See Index formula for full methodology and calculations.
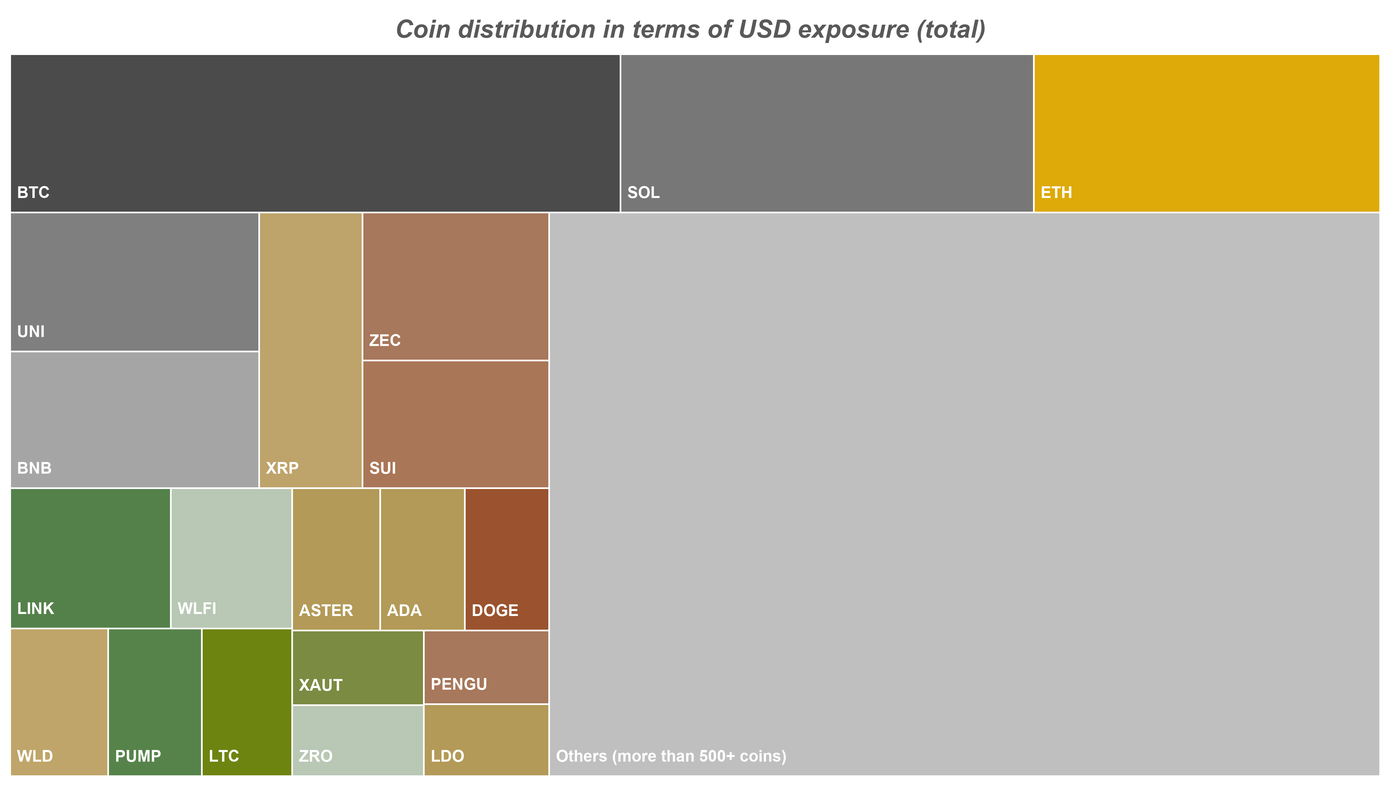
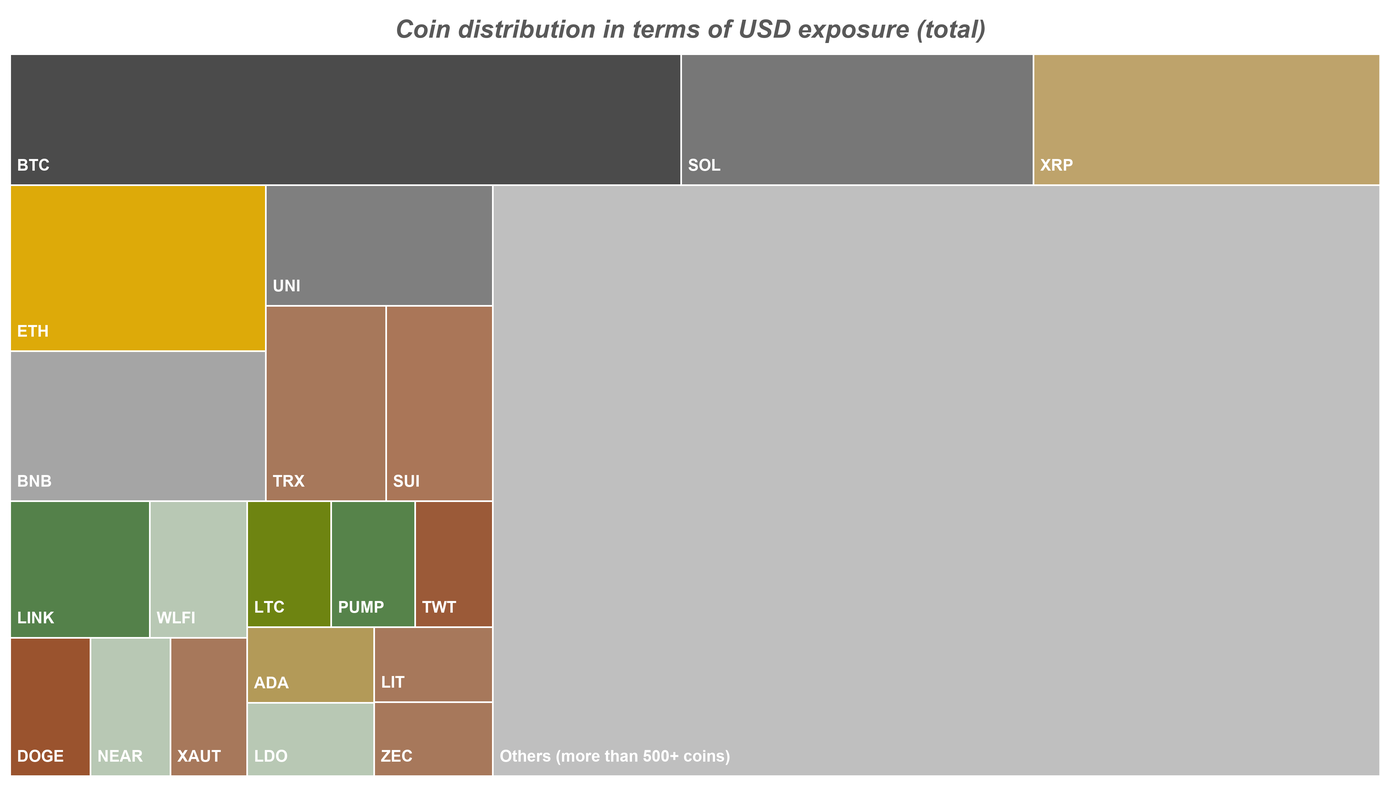
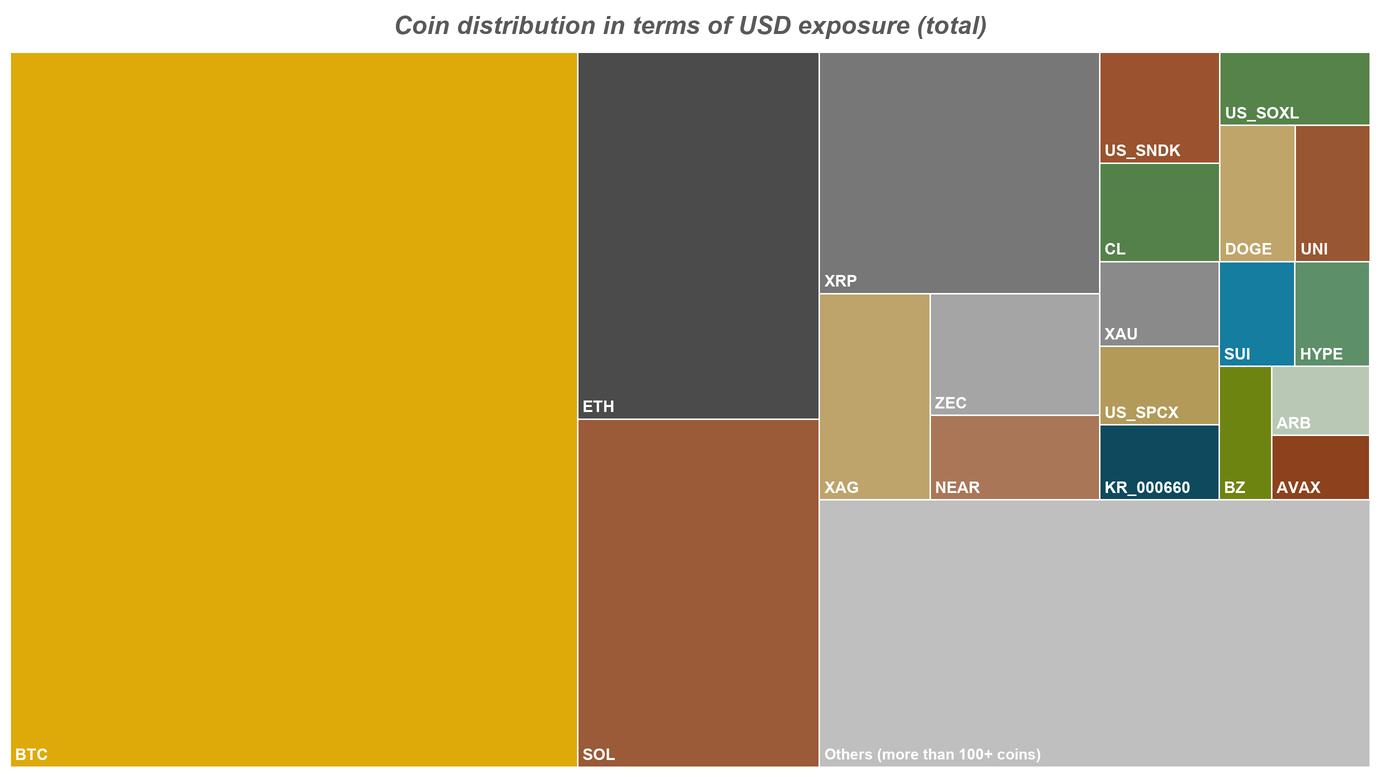
To assess the dispersion across coins, we defined the aggregation degree β (ranging from 0 to 1). When β is closer to 1, it indicates that the investment is more concentrated in a few coins, while when β is closer to 0, it indicates that the investment is more diversified.
The aggregation degree, β, declined from 0.03 in August to 0.02 in September 2026, indicating that coin exposure remained well diversified across both months, with a modest further reduction in concentration in September.
2026-08 | Coin exposure treemap | delta neutral
2026-09 | Coin exposure treemap | delta neutral
Calculation method
The Market Neutral index is based on data from the 1ndex platform, with NAV rebased to 1.000 at the start of each monthly reporting period to facilitate performance comparisons. Index-level performance and constituent observations provide the basis for the return and risk analysis, while detailed trading team data offers additional insight into strategy execution, return composition and coin-level exposure. The two datasets are complementary and may differ in sample coverage.
2026-08 | market neutral index
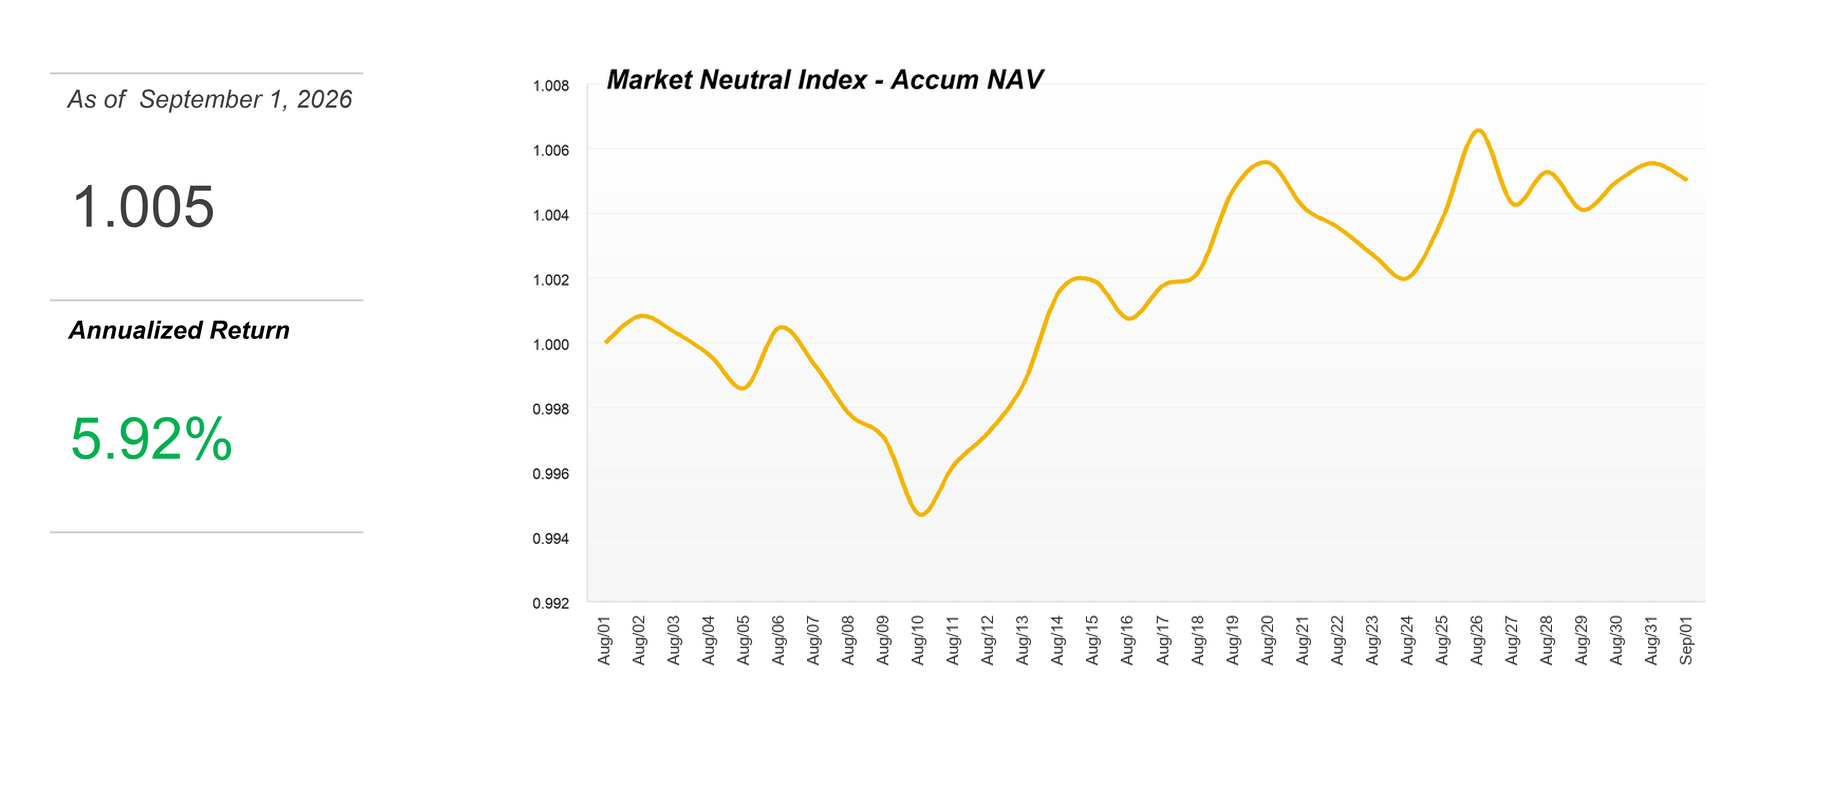
2026-09 | market neutral index
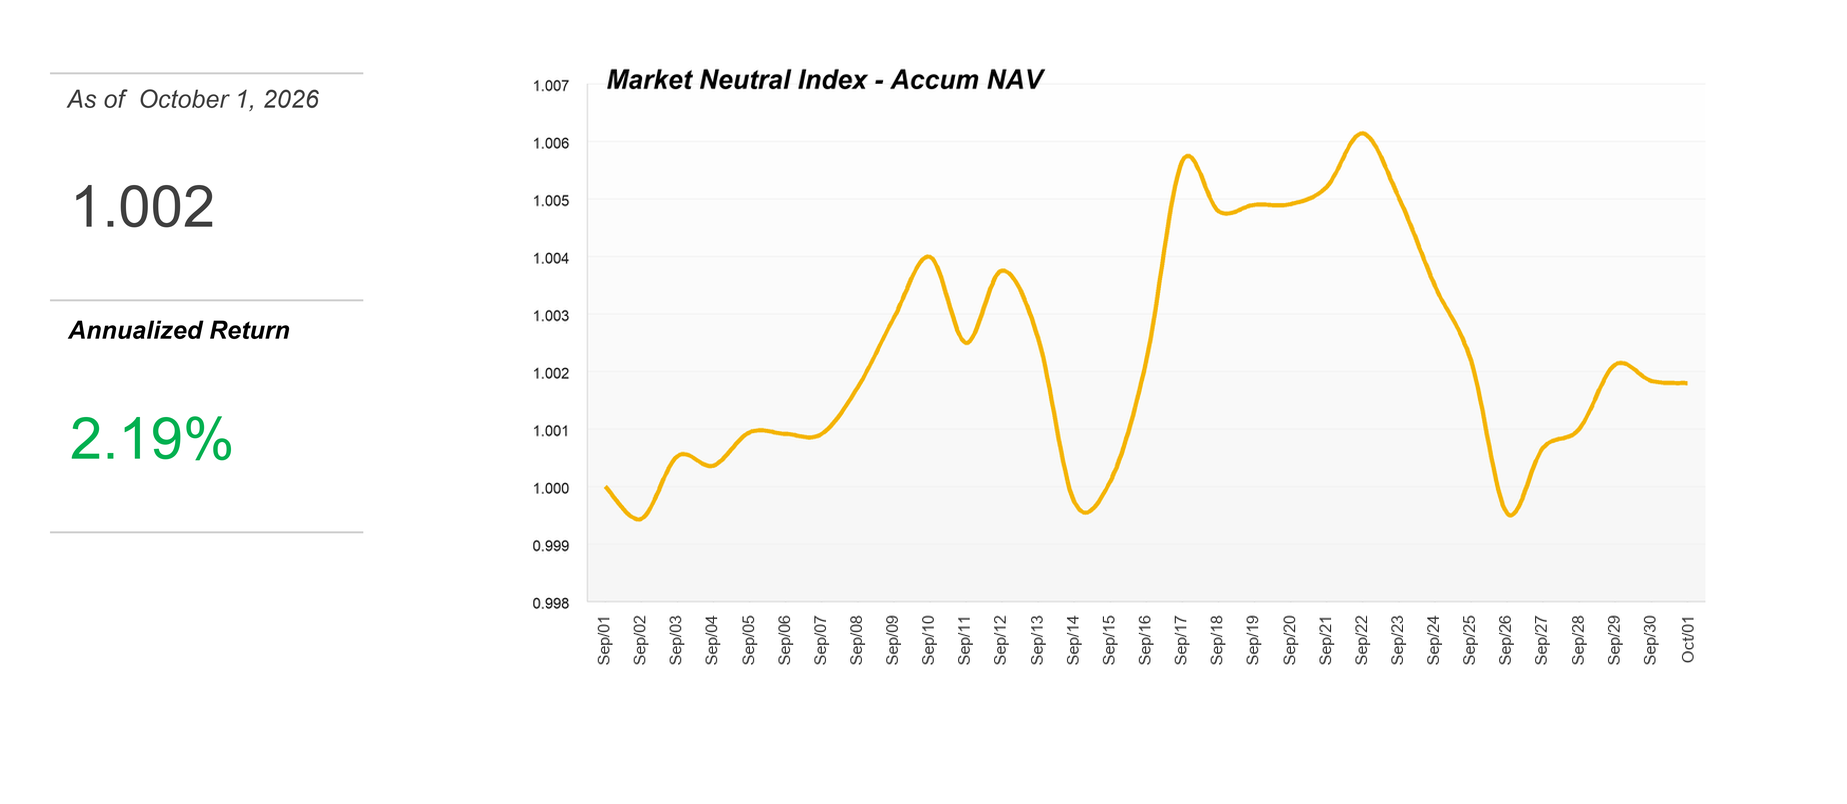
Note: We use the arithmetic mean instead of the weighted average because the current sample size is relatively small, as weighted averages cannot accurately reflect actual team weights. Therefore, the impact of principal has been normalized.
Indicators
Profit and Loss (PNL) and Risk
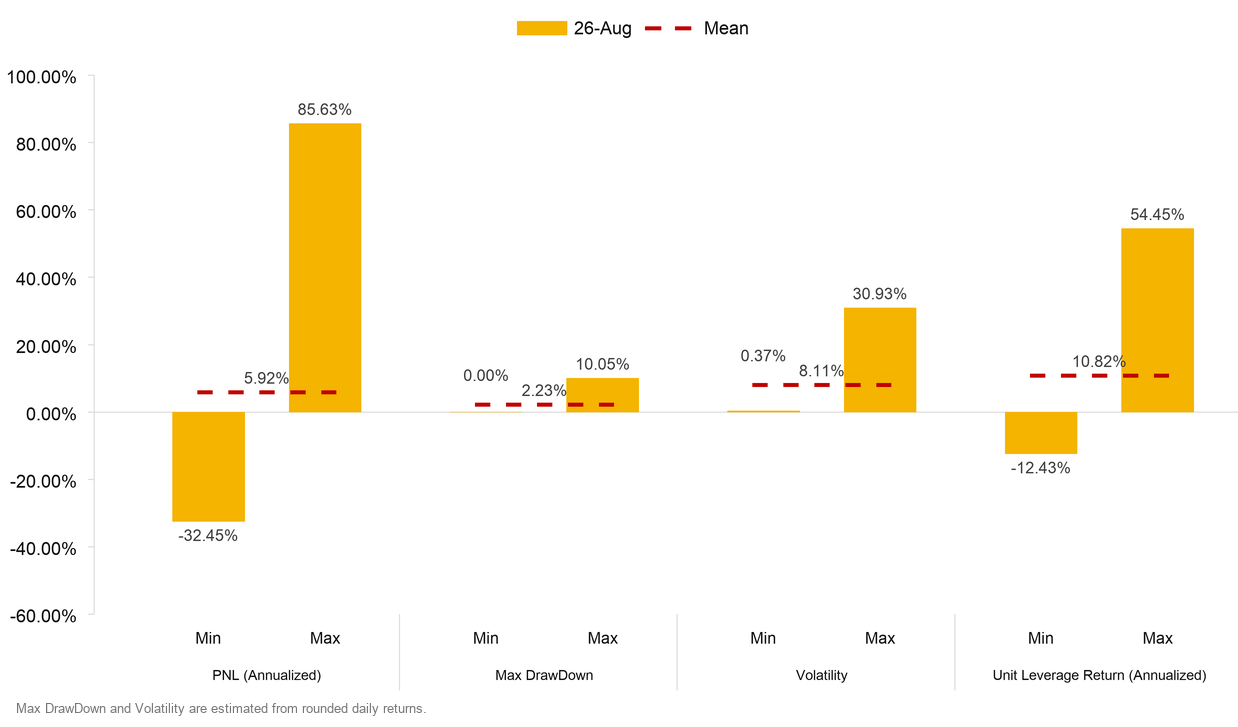
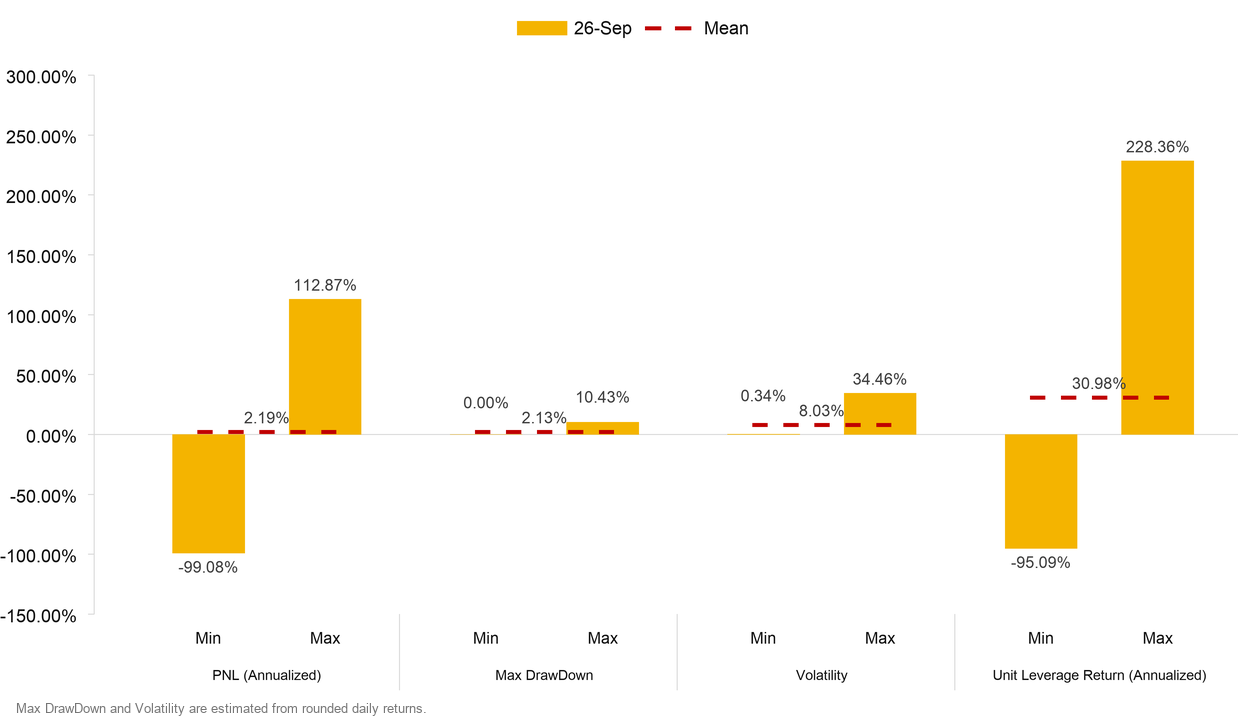
Market Neutral mean annualized return was 5.92% in August and 2.19% in September. Estimated mean maximum drawdown across participating strategies was 2.23% in August and 2.13% in September.
2026-08 | PNL and risk | market neutral
2026-09 | PNL and risk | market neutral
Note: see Index formula for full methodology and calculations.
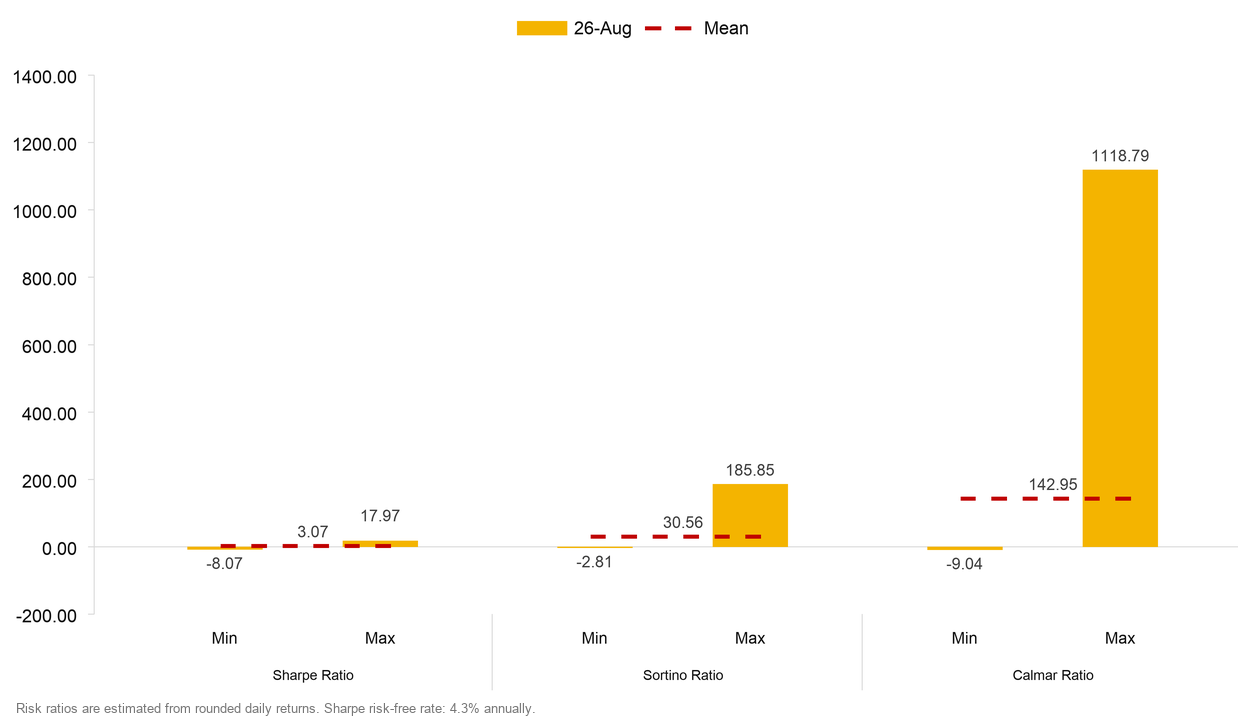
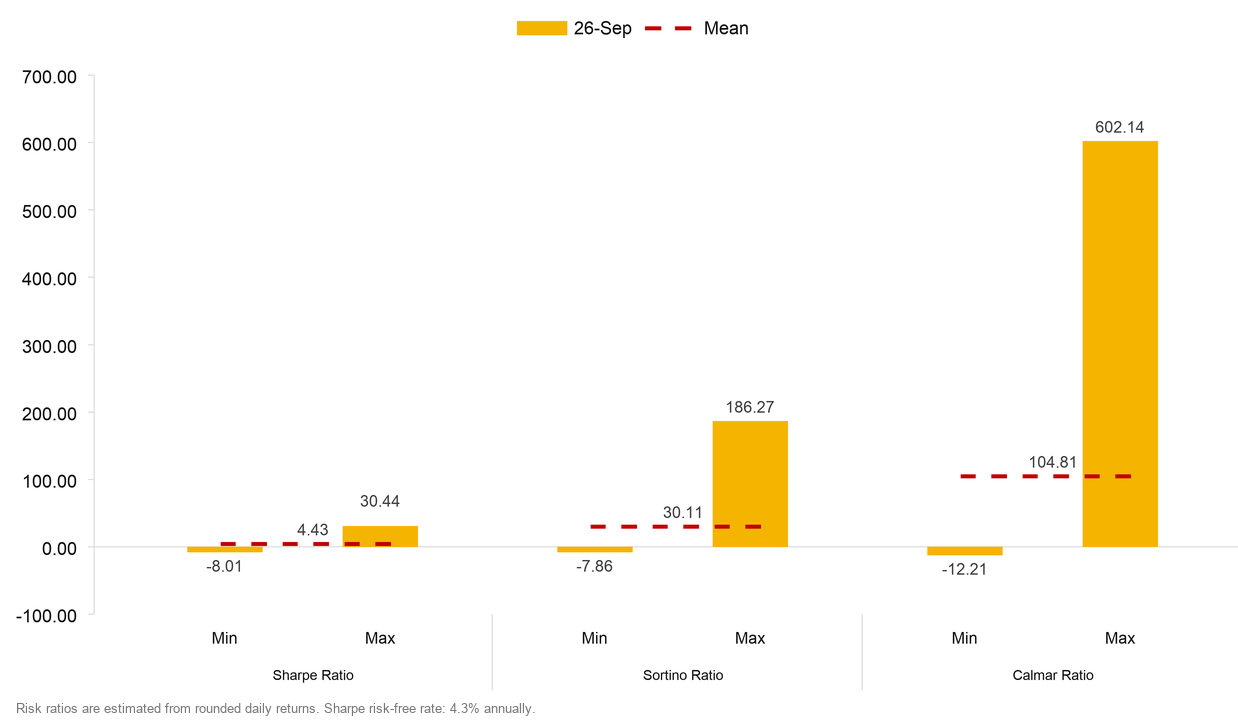
We further assessed risk-adjusted performance through Sharpe Ratio (measuring return per unit of total risk), Sortino Ratio (focusing specifically on downside risk), and Calmar Ratio (evaluating returns relative to maximum drawdown), providing a comprehensive framework to gauge strategy effectiveness across varying market environments.
2026-08 | Risk-adjusted return | market neutral
2026-09 | Risk-adjusted return | market neutral
Note: see Index formula for full methodology and calculations.
Strategy Features
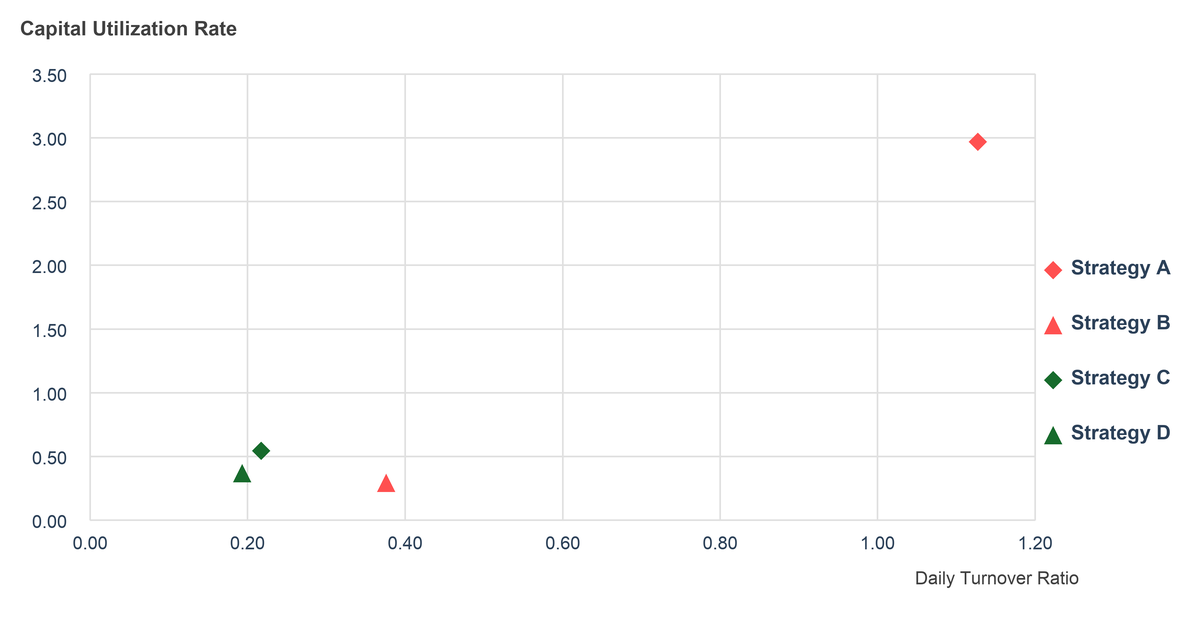
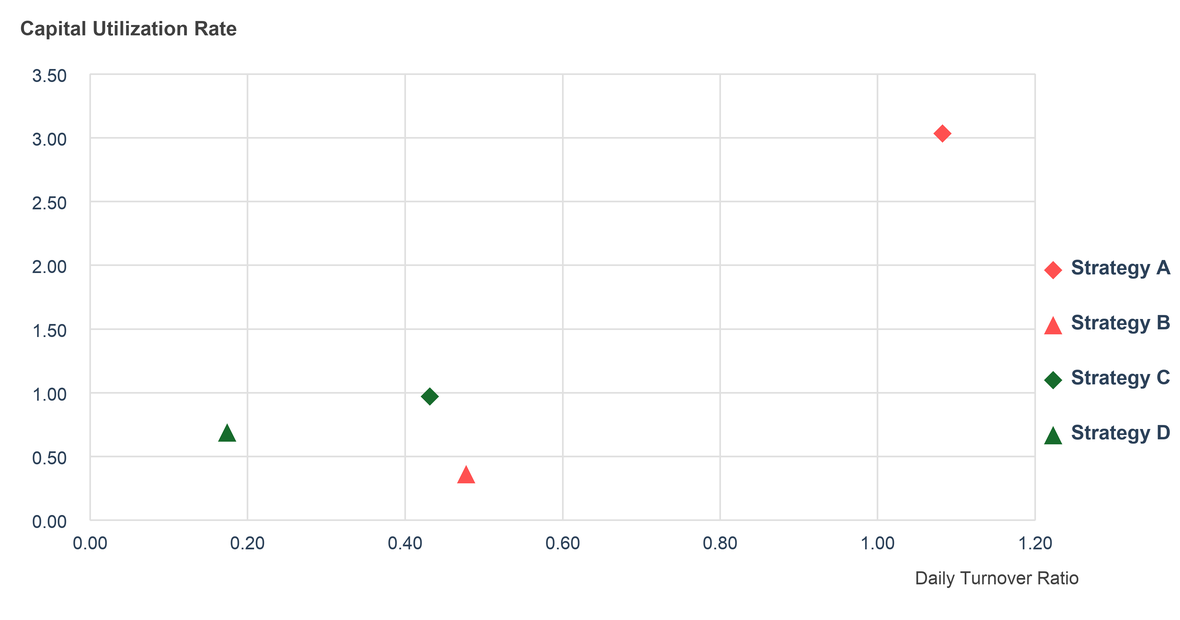
This section introduces two activity and capital-efficiency metrics for Market Neutral strategy evaluation: Daily Turnover Ratio and Capital Utilization Rate.
Daily Turnover Ratio measures average daily trading volume relative to gross exposure, providing an indication of trading intensity. Higher ratios reflect more active portfolio turnover.
Capital Utilization Rate measures average daily trading volume relative to net assets, indicating the level of trading activity supported by the strategy’s capital base. Higher ratios reflect greater trading activity per unit of capital.
Daily turnover and capital utilization varied across the participating teams in both months, reflecting different trading activity and capital deployment profiles.
2026-08 | Daily turnover ratio and capital utilization | market neutral
2026-09 | Daily turnover ratio and capital utilization | market neutral
Note: see Index formula for full methodology and calculations.
Coin Distributions
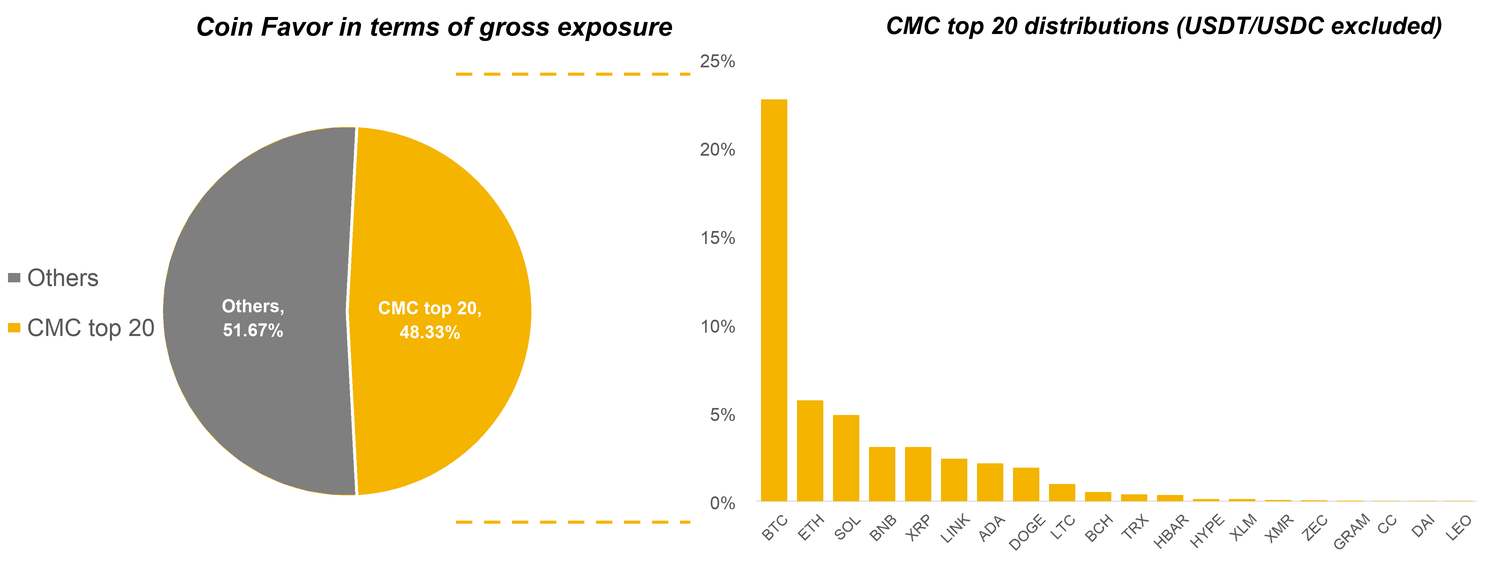
We aggregated daily position snapshots provided by participating trading teams over two monthly reporting periods: August 1 to September 1 and September 1 to October 1, 2026, with each period measured at a 00:00 UTC cut-off. Absolute USD exposure was consolidated by underlying asset to assess the allocation between CMC top-20 assets and other coins, as well as the concentration and diversification of each strategy’s coin exposure.
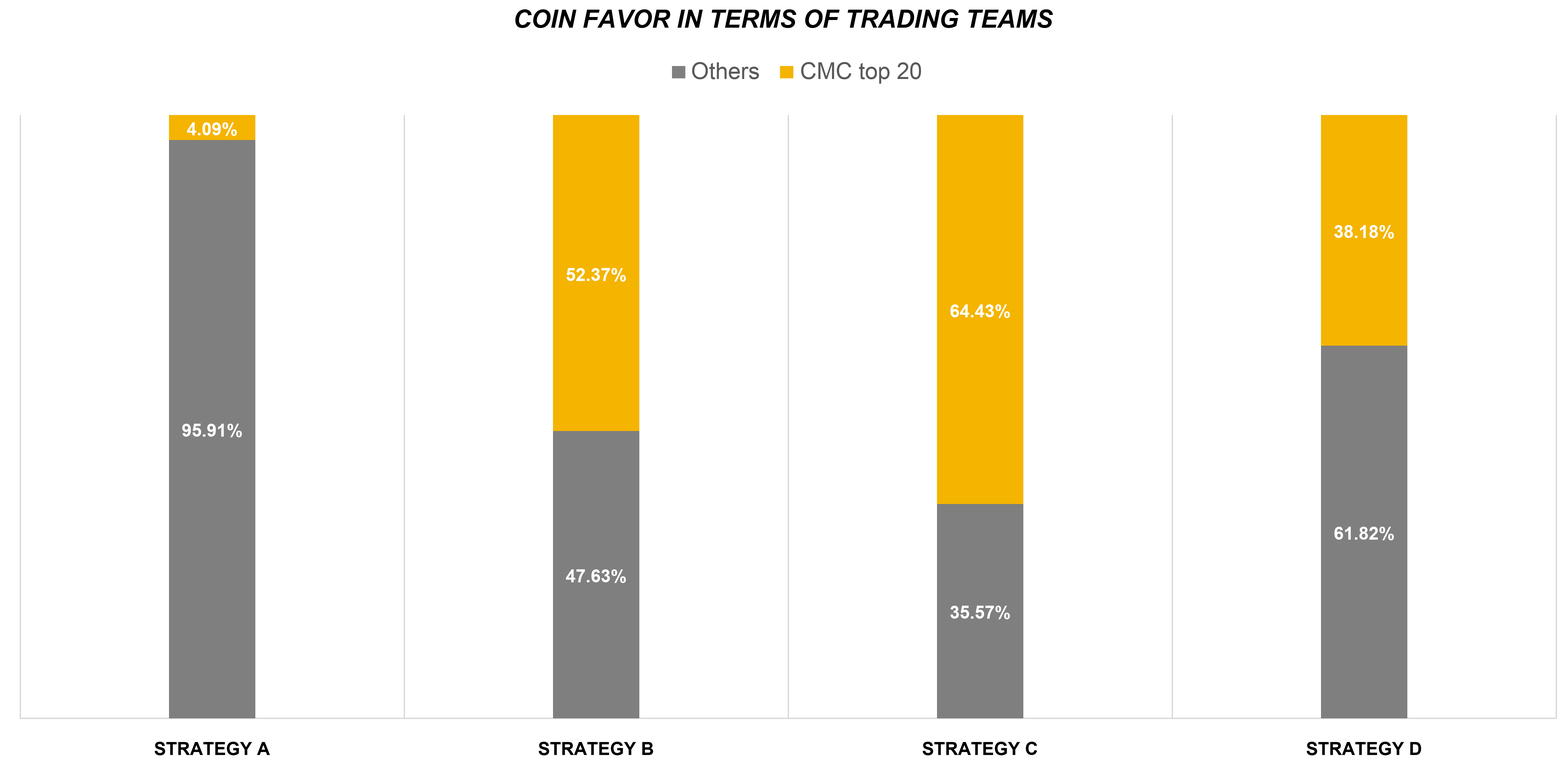
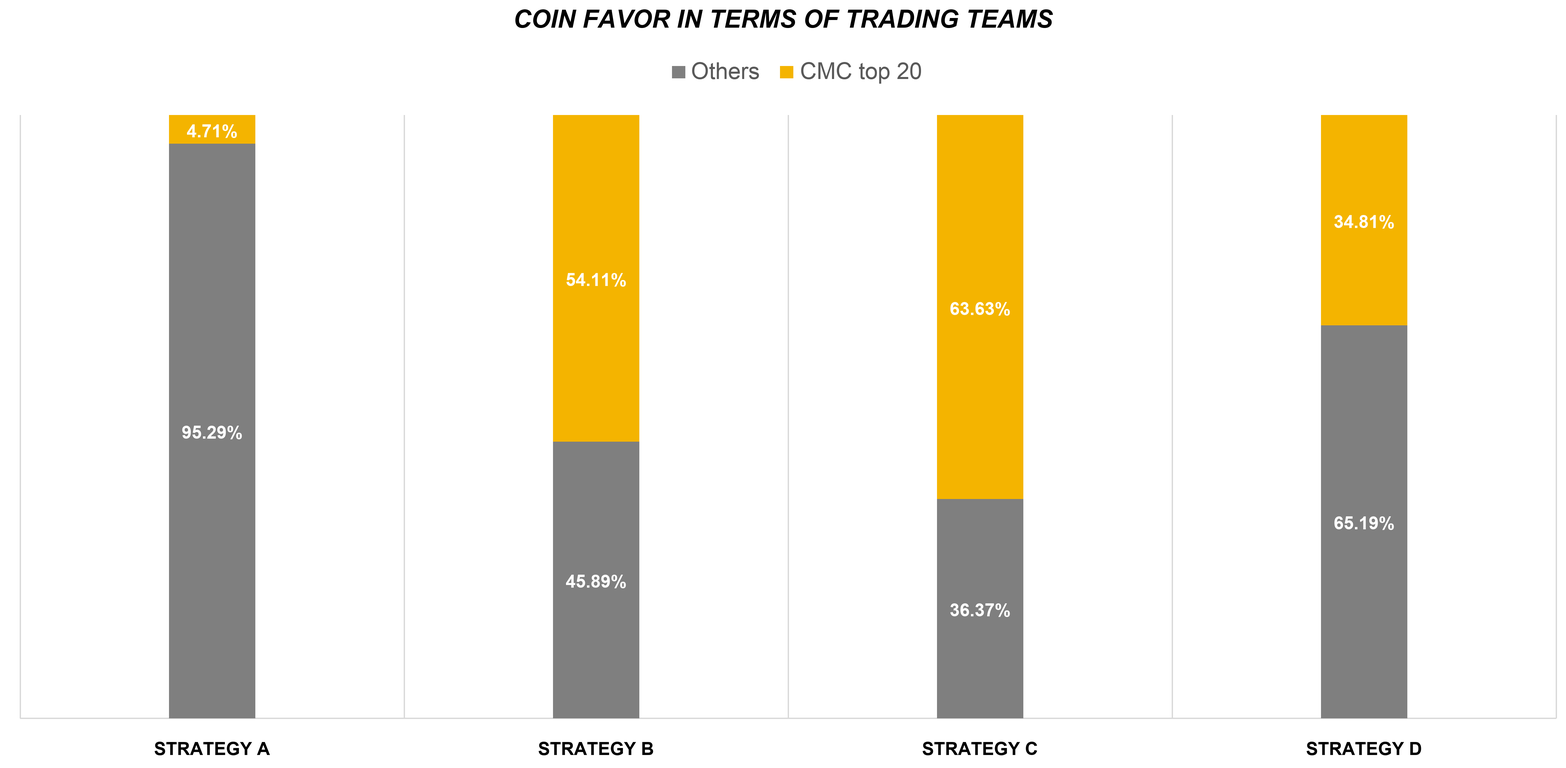
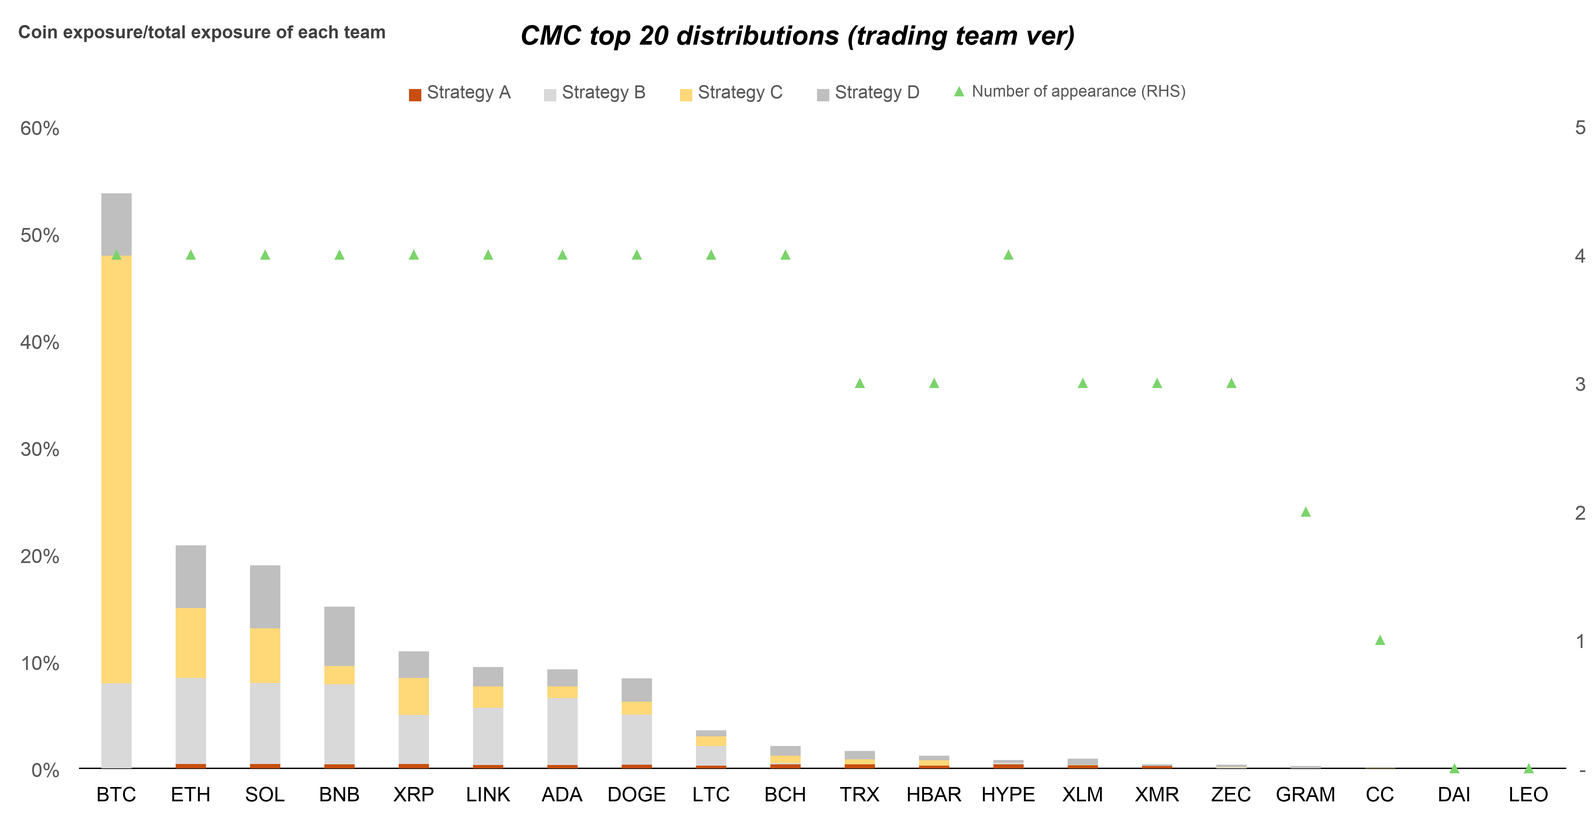
Overall, exposure was broadly balanced between large-cap coins (CMC top 20) and other assets across the two months, with a modest large-cap tilt in August giving way to a slightly higher allocation to other assets in September. Among large-cap coins, BTC represented the largest exposure share in our sample of participating teams in both months.
2026-08 | Coin distribution | market neutral
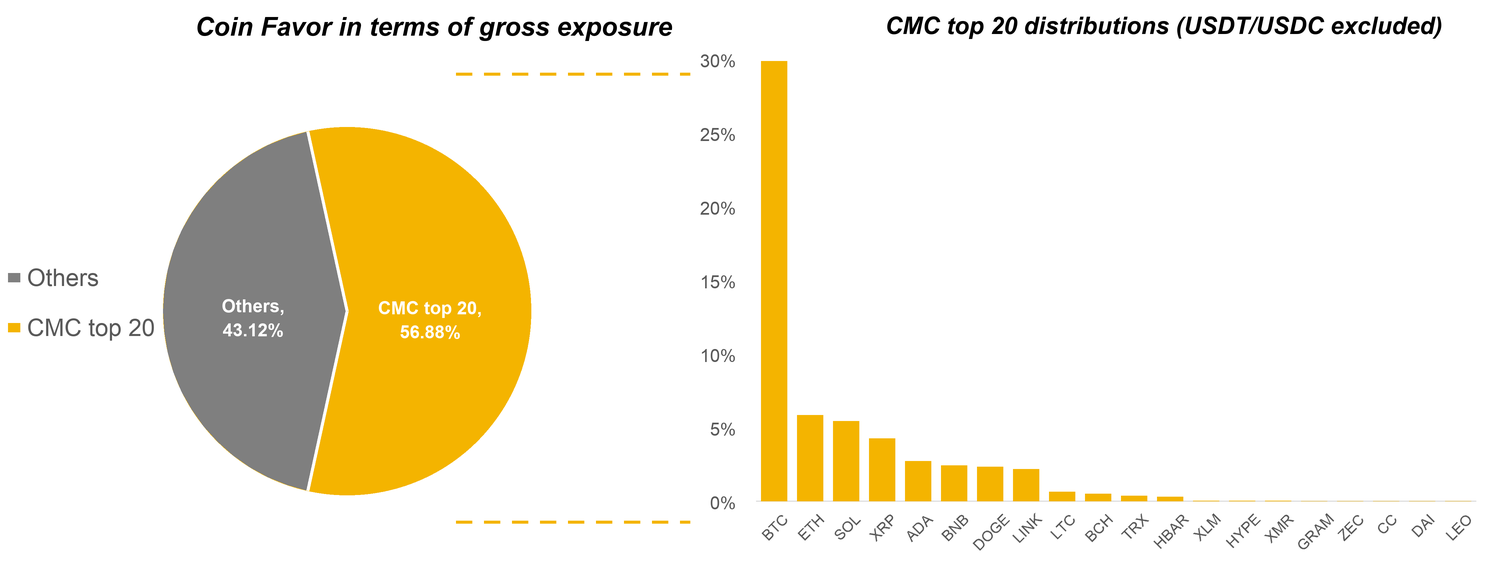
2026-09 | Coin distribution | market neutral
2026-08 | Coin favor by team | market neutral
2026-09 | Coin favor by team | market neutral
2026-08 | CMC top-20 exposure by team | market neutral
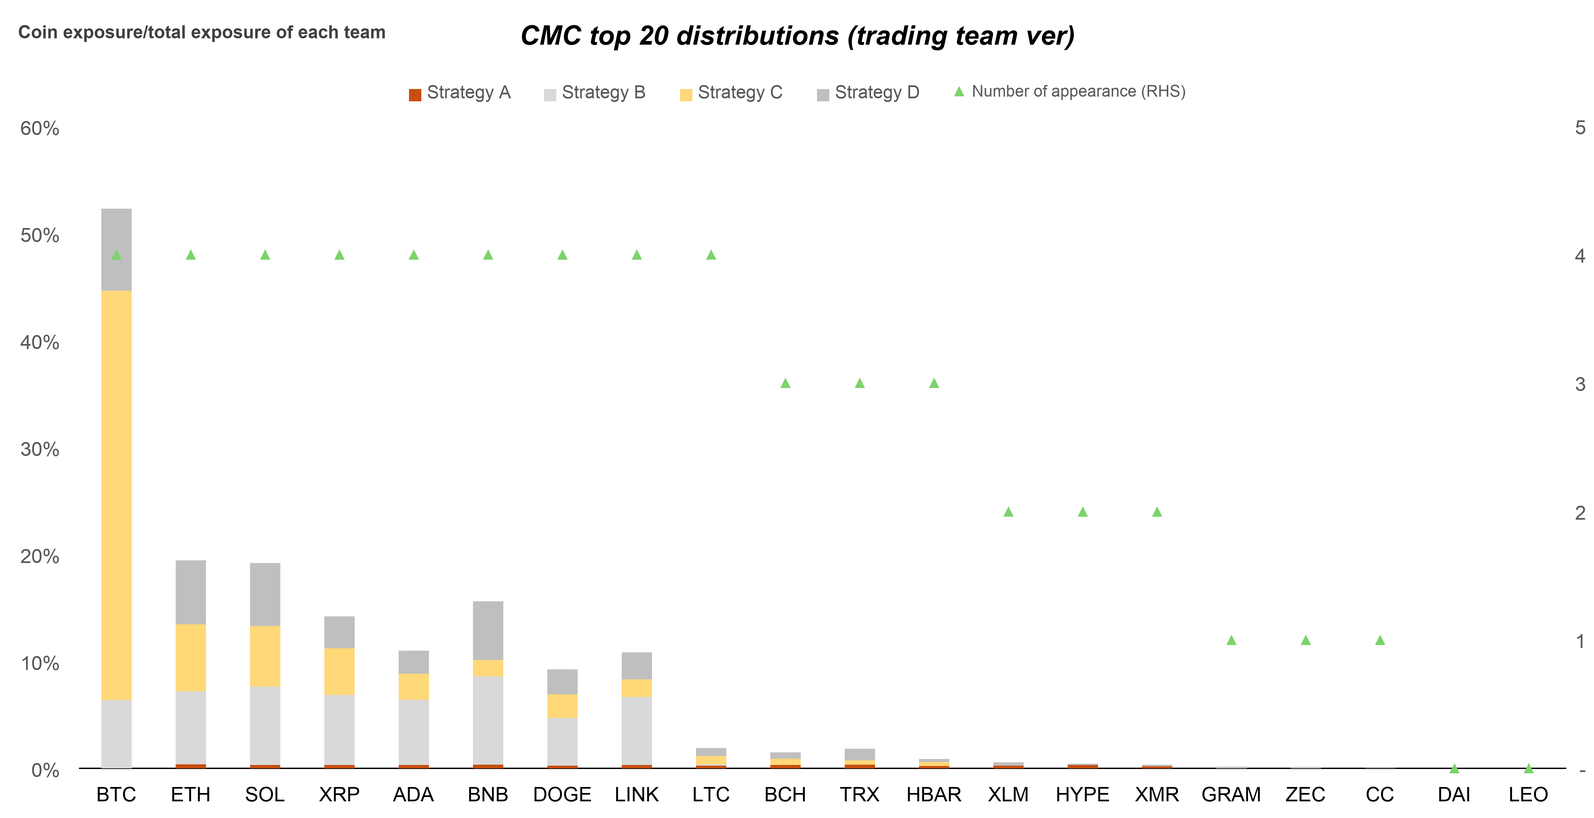
2026-09 | CMC top-20 exposure by team | market neutral
Note:
-
USD exposure = Delta * Underlying Price
-
See Index formula for full methodology and calculations.
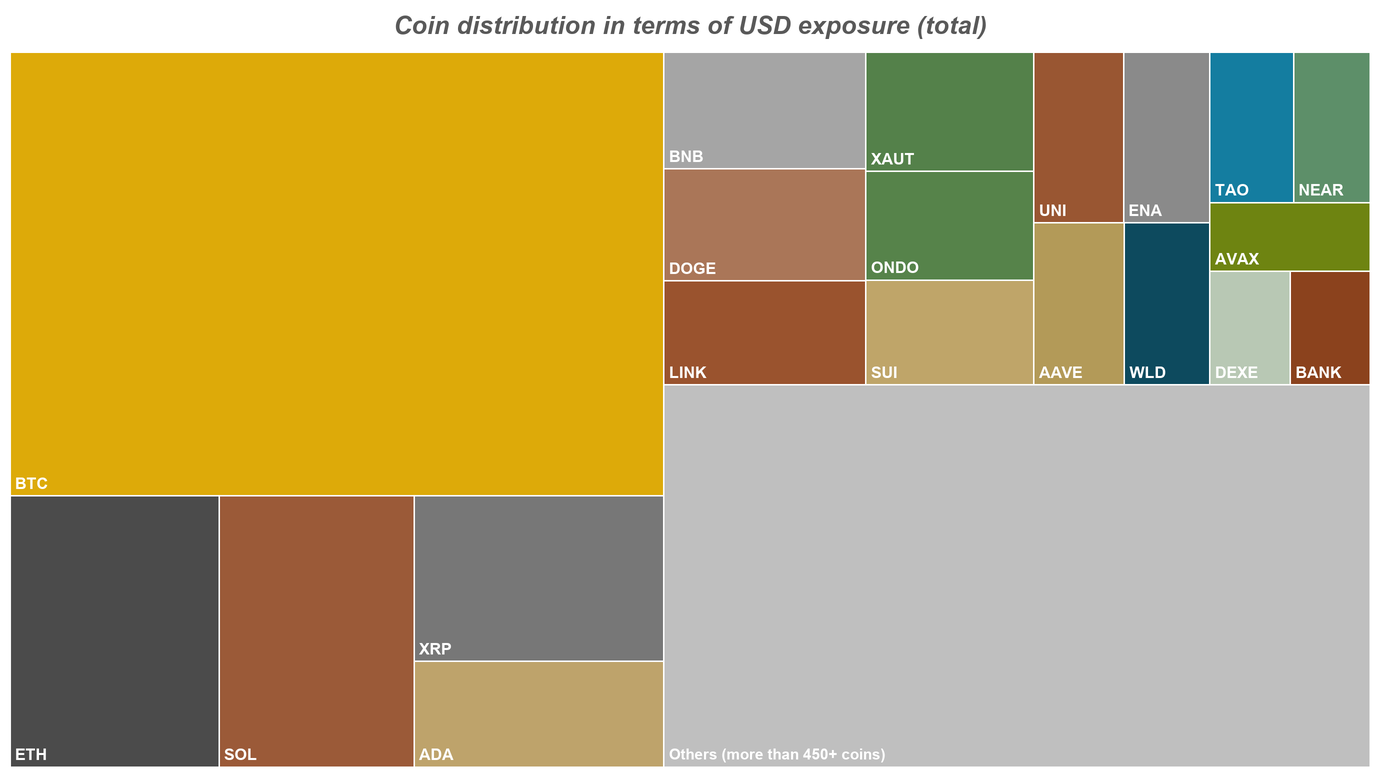
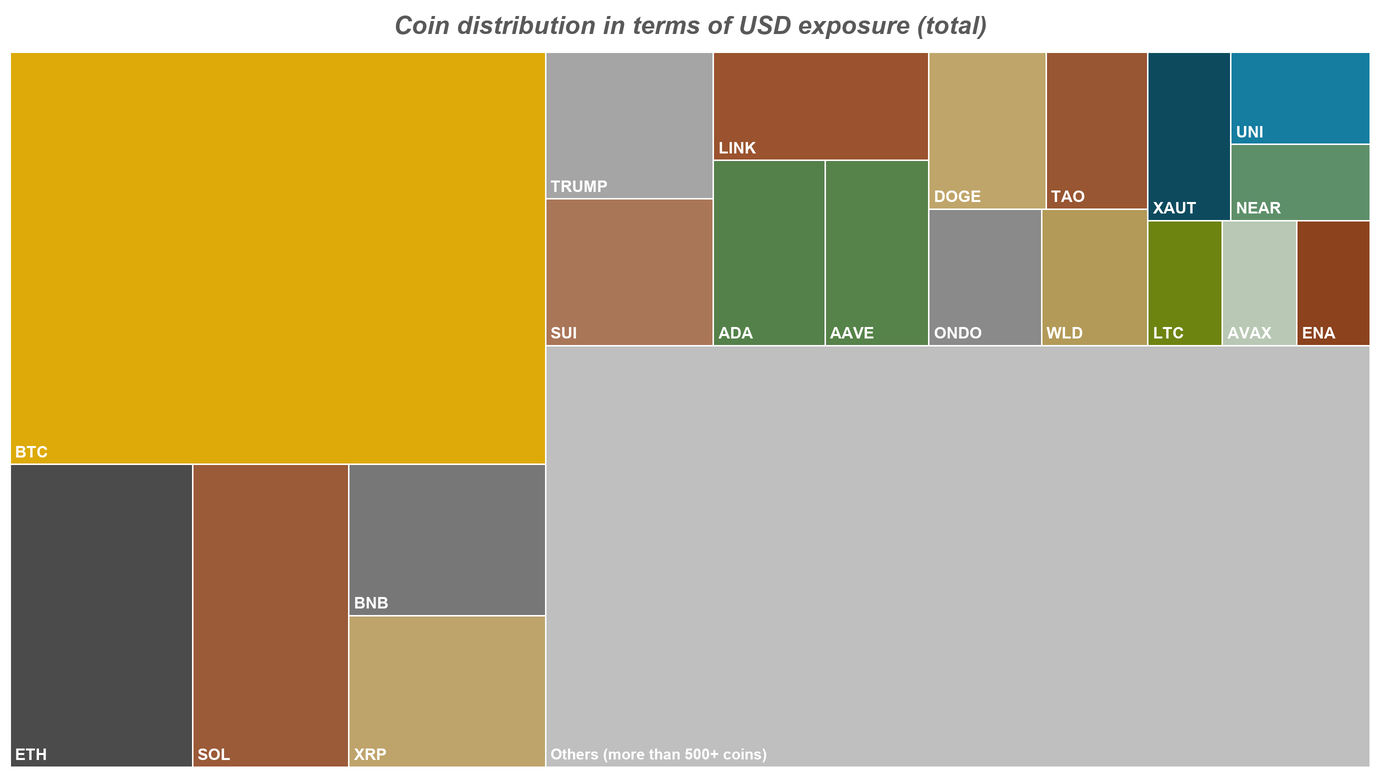
To assess the dispersion across coins, we defined the aggregation degree β (ranging from 0 to 1). When β is closer to 1, it indicates that the investment is more concentrated in a few coins, while when β is closer to 0, it indicates that the investment is more diversified.
The aggregation degree, β, declined from 0.10 in August to 0.06 in September 2026, indicating that coin exposure remained diversified across both months, with a further reduction in concentration in September.
2026-08 | Coin exposure treemap | market neutral
2026-09 | Coin exposure treemap | market neutral
Calculation method
The Directional index is based on data from the 1ndex platform, with NAV rebased to 1.000 at the start of each monthly reporting period to facilitate performance comparisons. Index-level performance and constituent observations provide the basis for the return and risk analysis, while detailed trading team data offers additional insight into strategy execution, return composition and coin-level exposure. The two datasets are complementary and may differ in sample coverage.
2026-08 | directional index
2026-09 | directional index
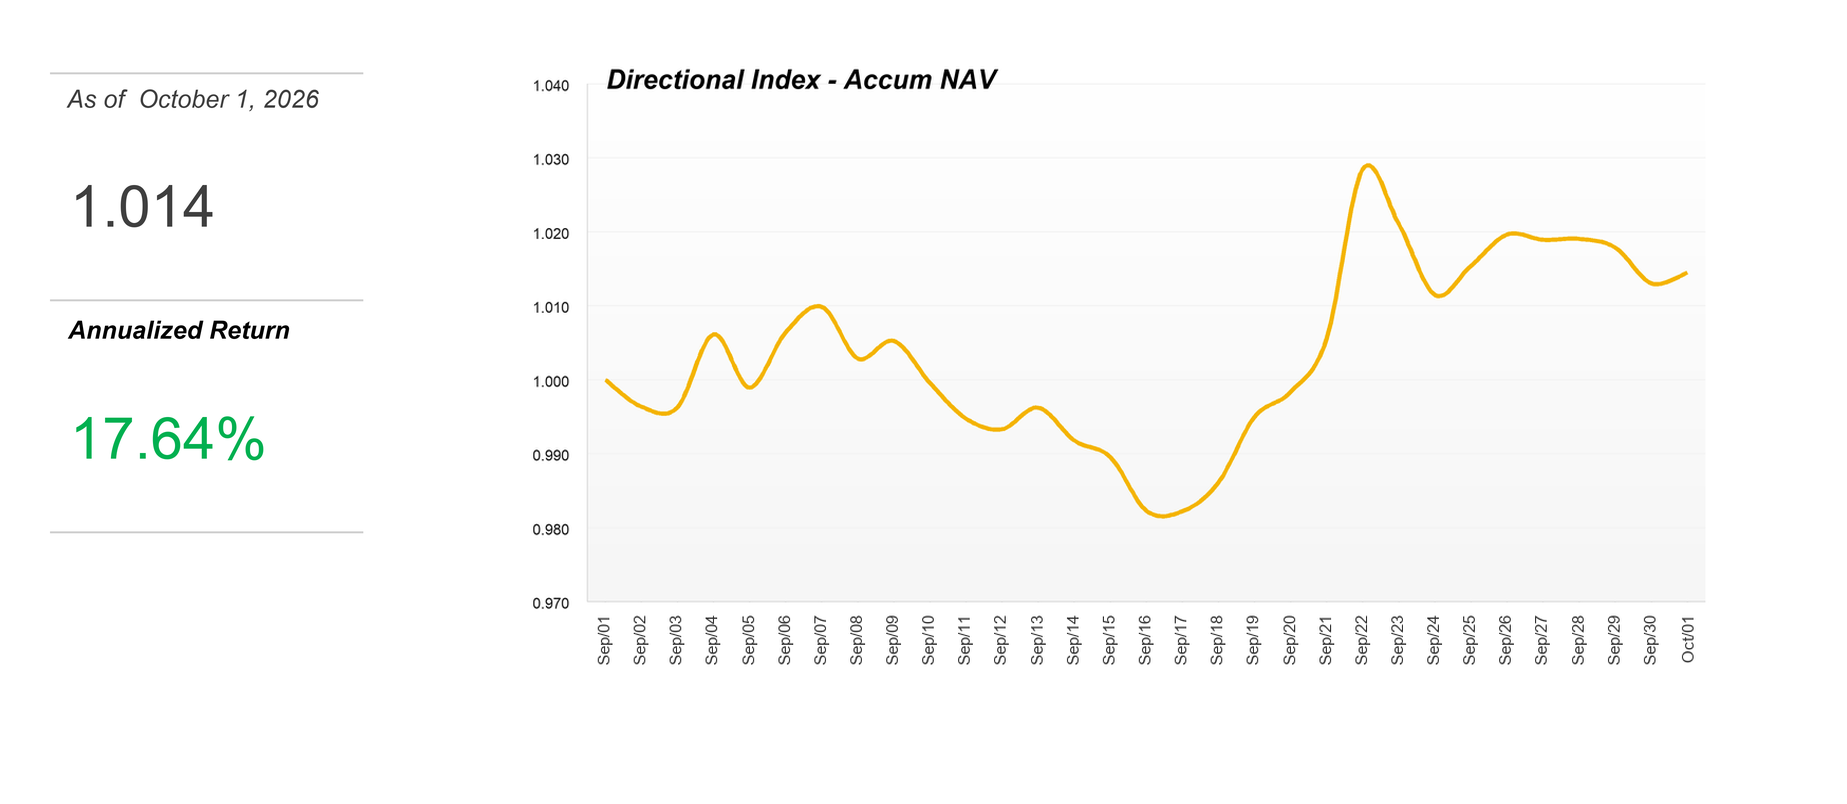
Note: We use the arithmetic mean instead of the weighted average because the current sample size is relatively small, as weighted averages cannot accurately reflect actual team weights. Therefore, the impact of principal has been normalized.
Indicators
Profit and Loss (PNL) and Risk
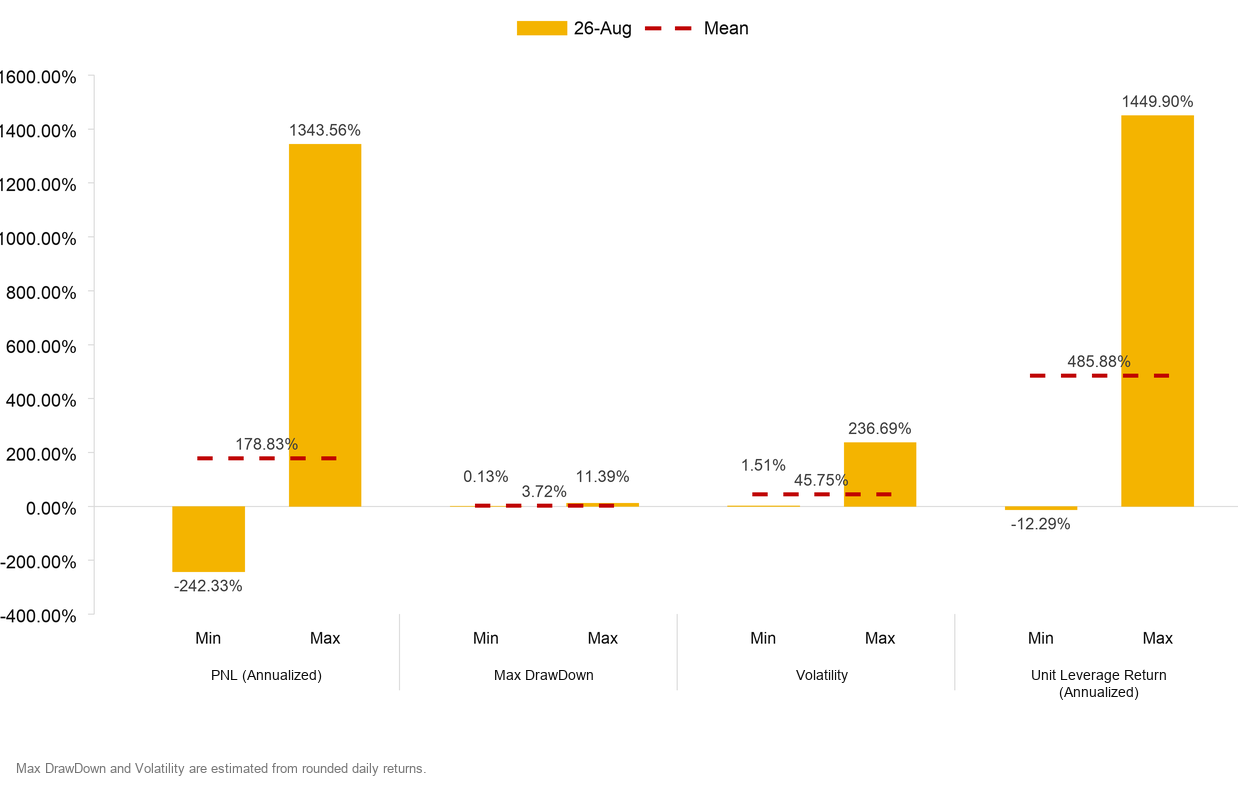
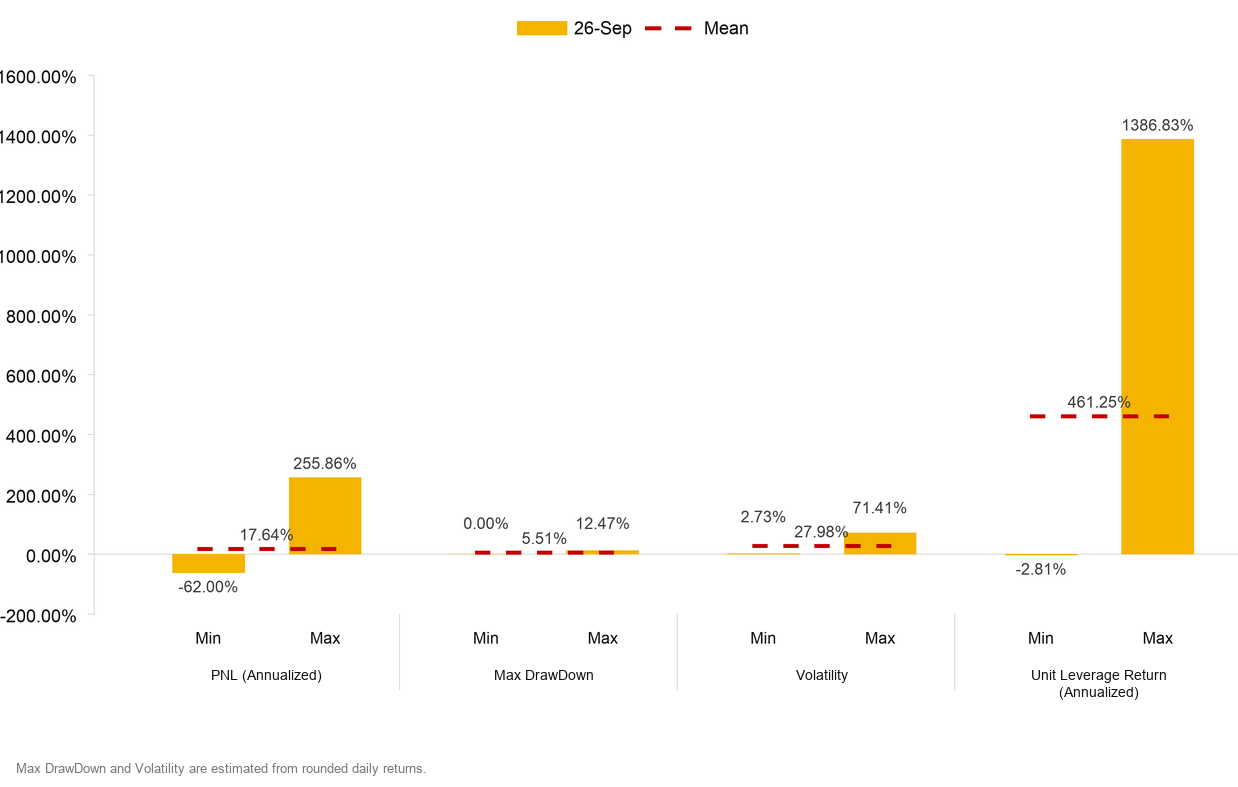
Directional mean annualized return was 178.83% in August and 17.64% in September. Estimated mean maximum drawdown across participating strategies was 3.72% in August and 5.51% in September.
2026-08 | PNL and risk | directional
2026-09 | PNL and risk | directional
Note: see Index formula for full methodology and calculations.
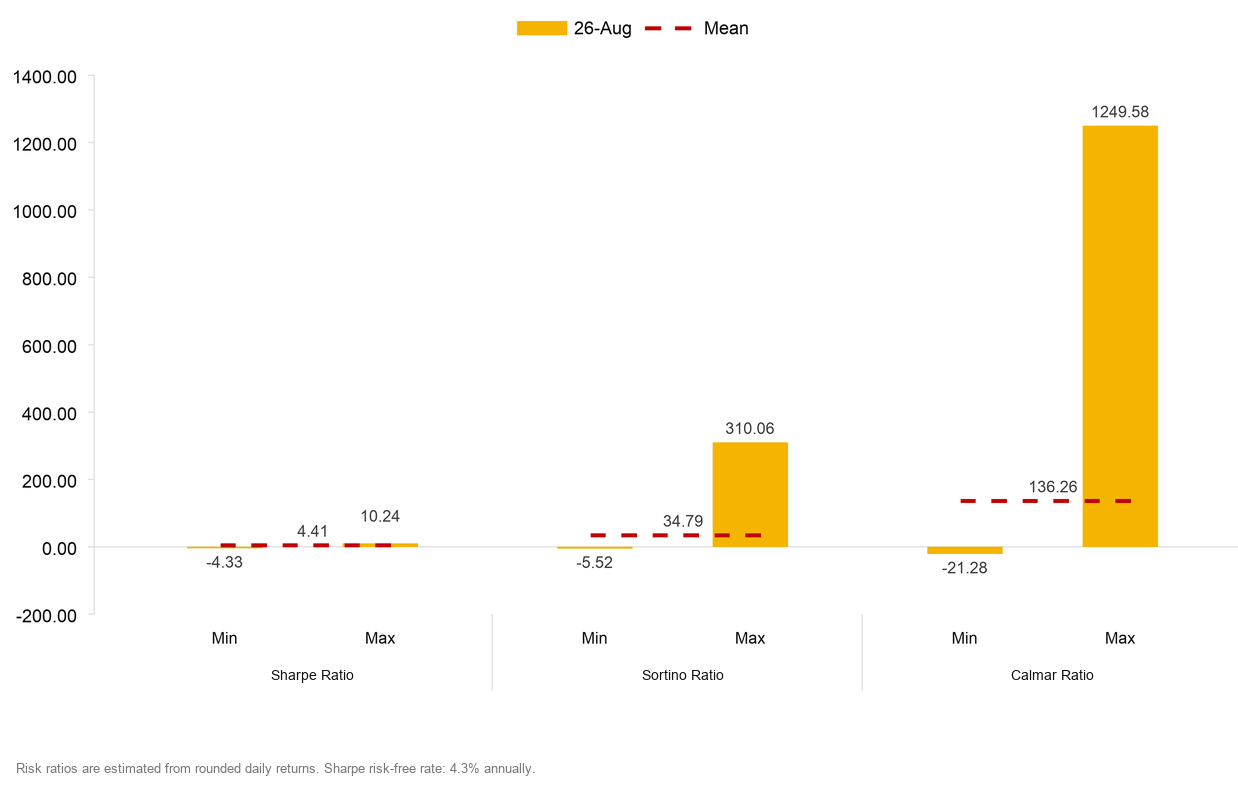
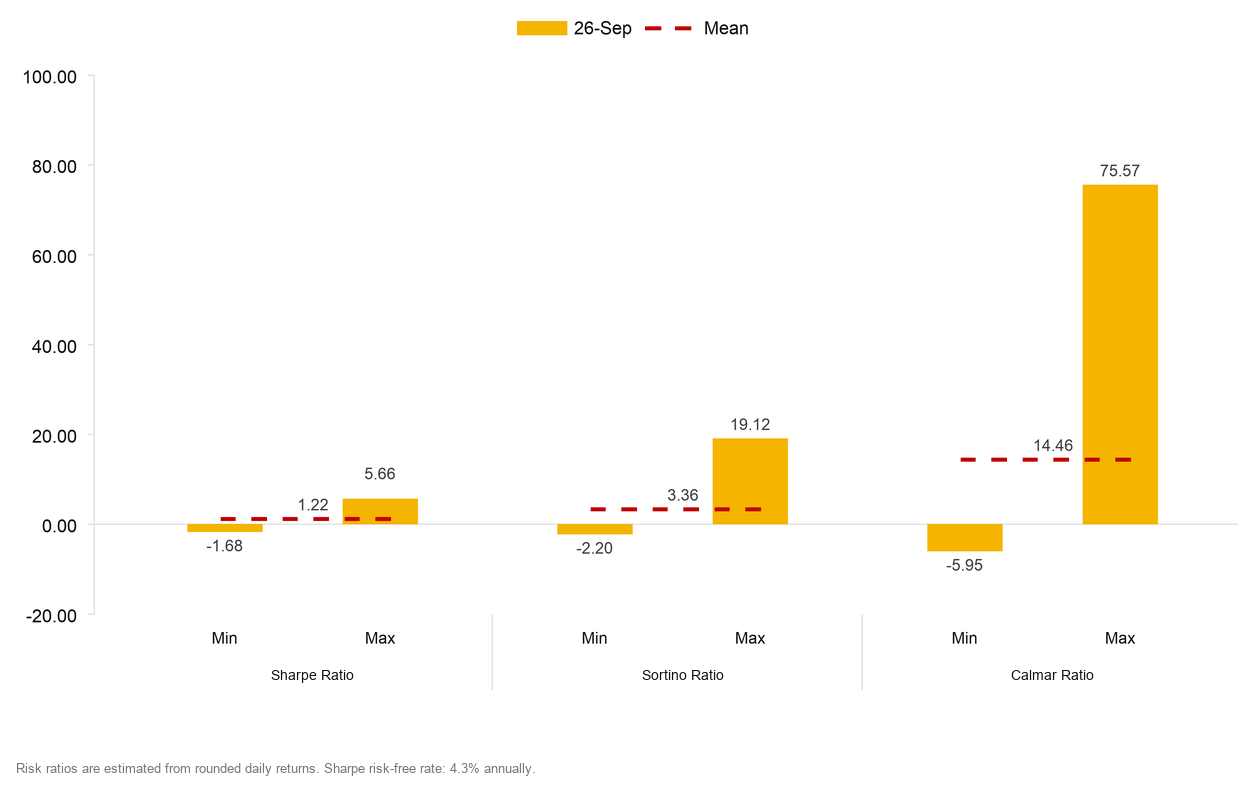
For a strategy defined by its volatility exposure, rigorous risk-adjusted assessment is critical. We employ the Sharpe Ratio to capture return per unit of total risk, the Sortino Ratio to isolate downside performance, and the Calmar Ratio to contextualize returns against peak-to-trough drawdowns. This multi-metric framework enables a nuanced evaluation of directional strategies' efficiency in harvesting macro beta while managing tail risks.
2026-08 | Risk-adjusted return | directional
2026-09 | Risk-adjusted return | directional
Note: see Index formula for full methodology and calculations.
Strategy Features
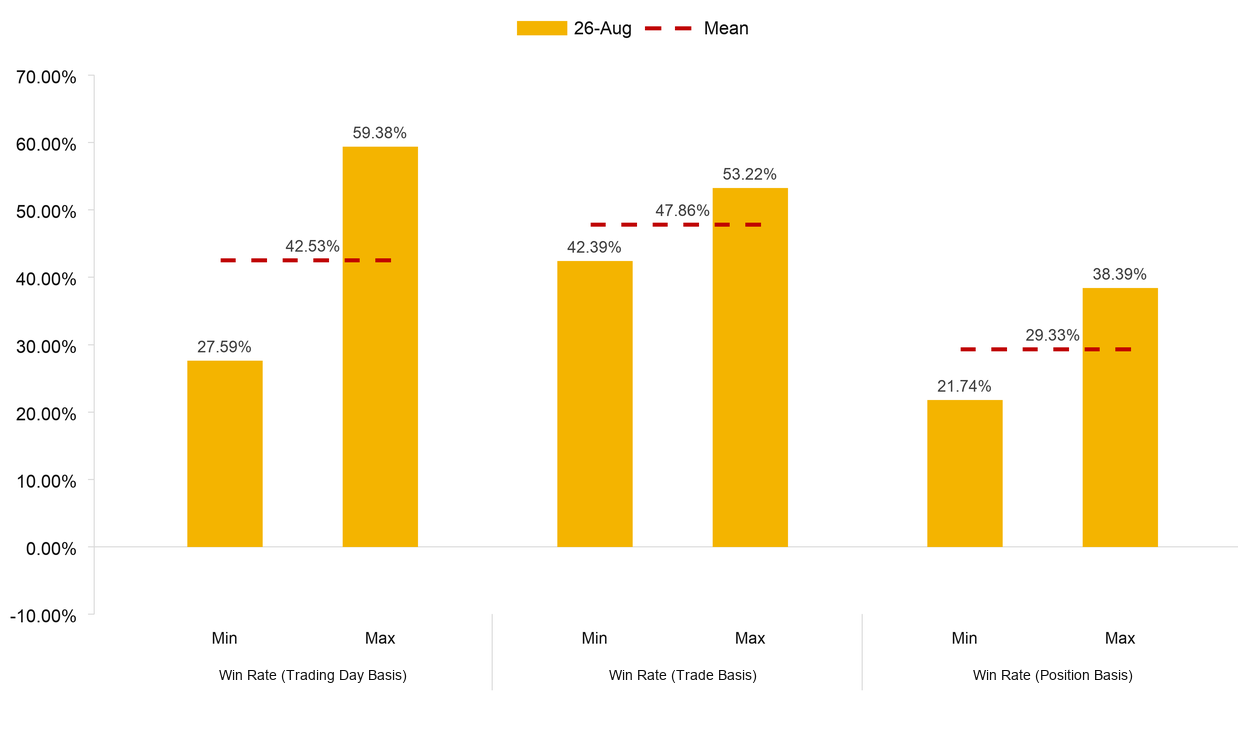
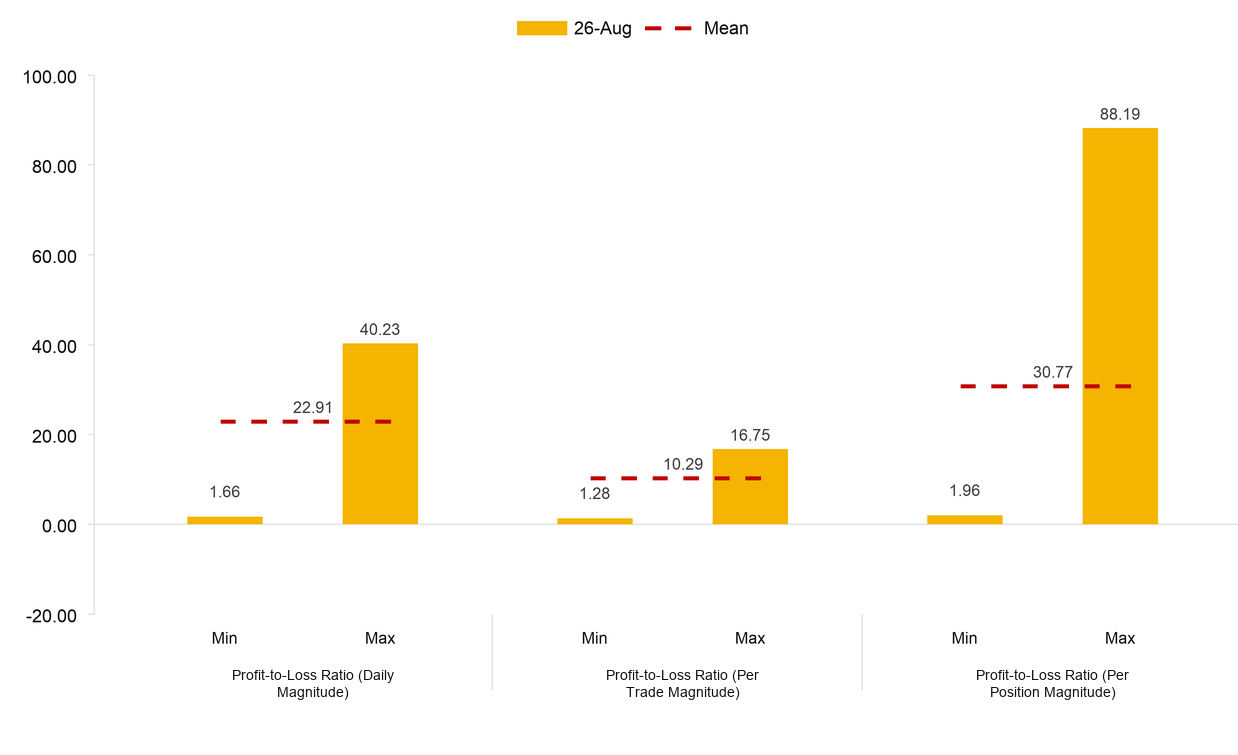
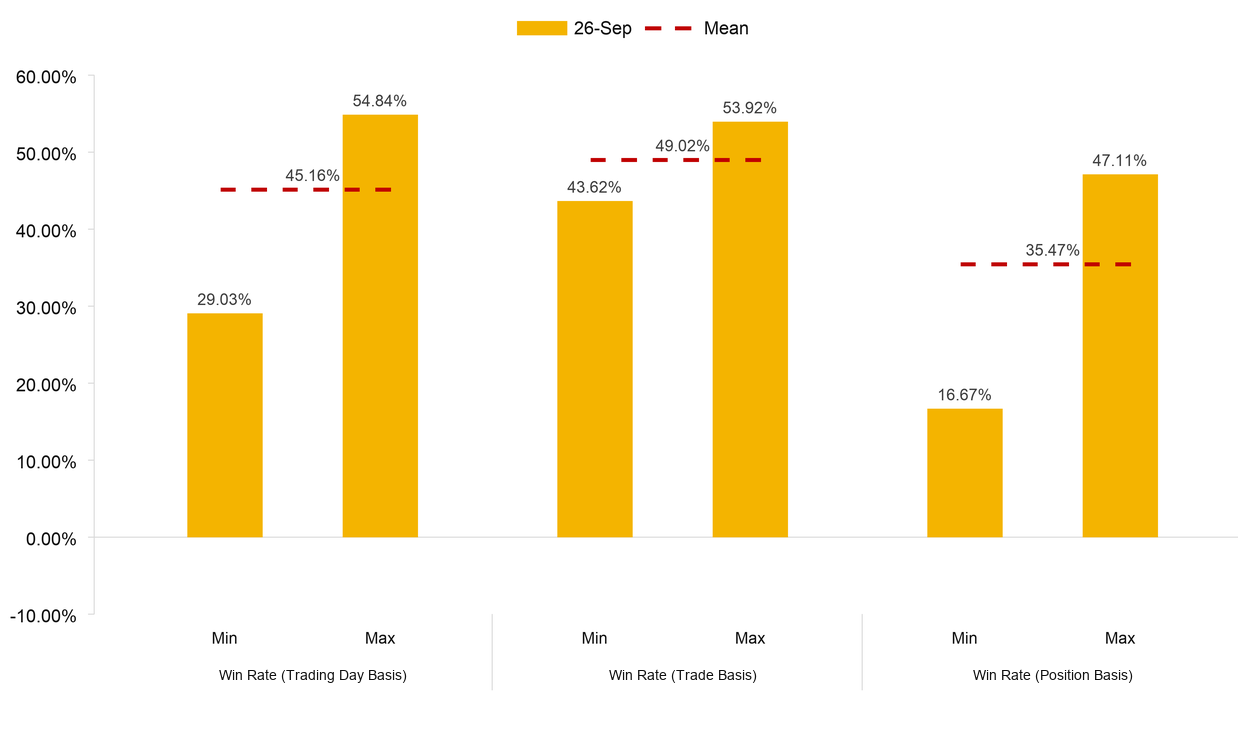
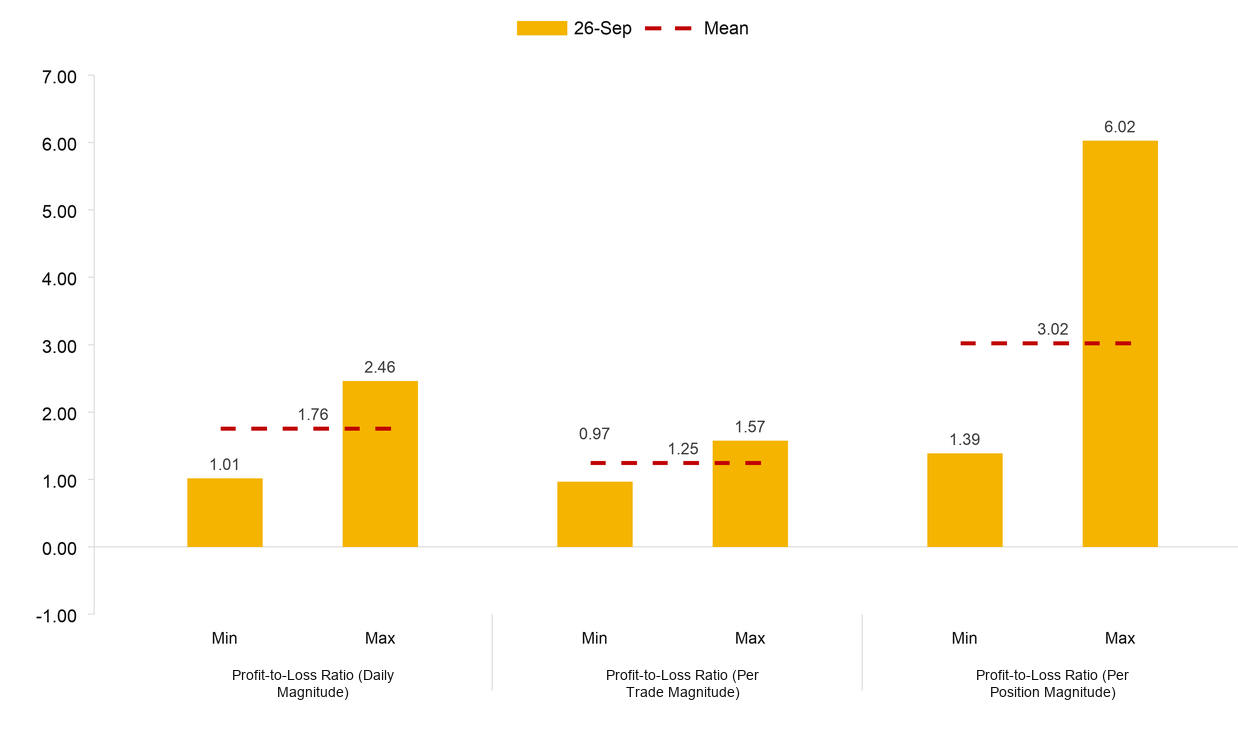
Win rate and profit-to-loss ratio offer complementary perspectives on Directional strategy performance, capturing the frequency of profitable outcomes and the magnitude of gains relative to losses. Both metrics are assessed on trading-day, trade and position bases.
The average trading-day win rate increased from 42.53% in August to 45.16% in September, while the average daily profit-to-loss ratio declined from 22.91 to 1.76. This suggests that profitable days became slightly more frequent in September, but the average gain on those days was smaller relative to the average loss on losing days.
2026-08 | Win rate and Profit-to-loss ratio | directional
2026-09 | Win rate and Profit-to-loss ratio | directional
Note: see Index formula for full methodology and calculations.
Coin Distributions
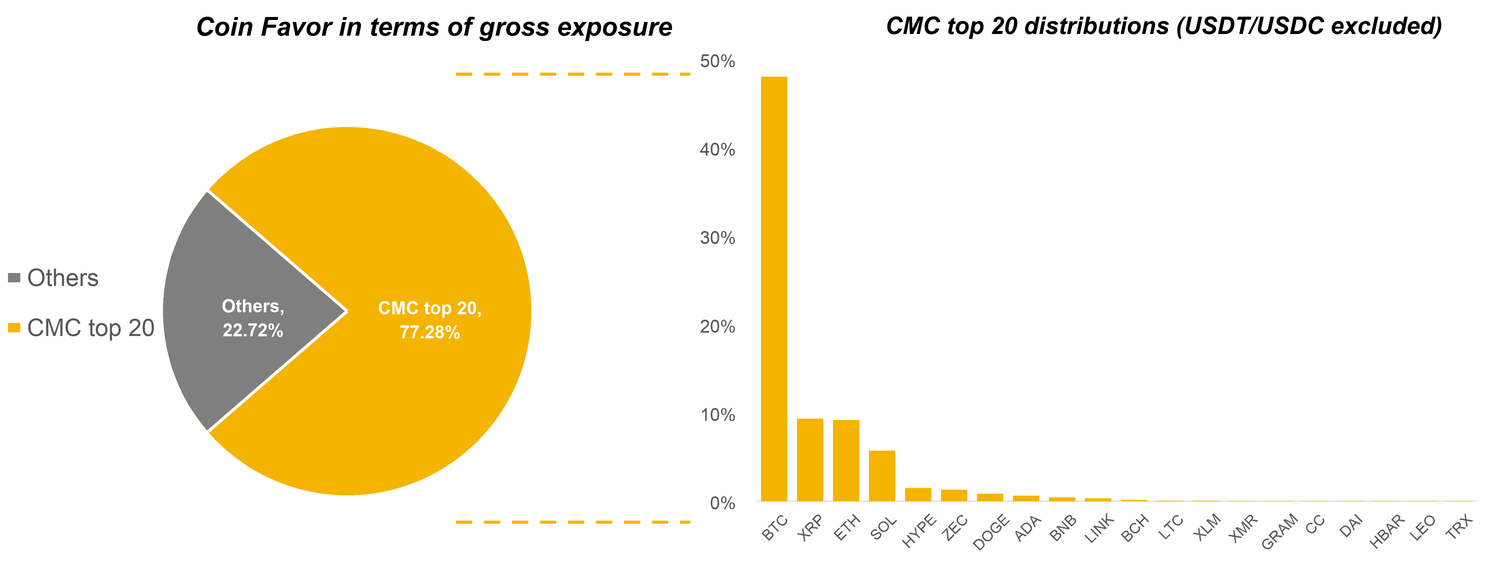
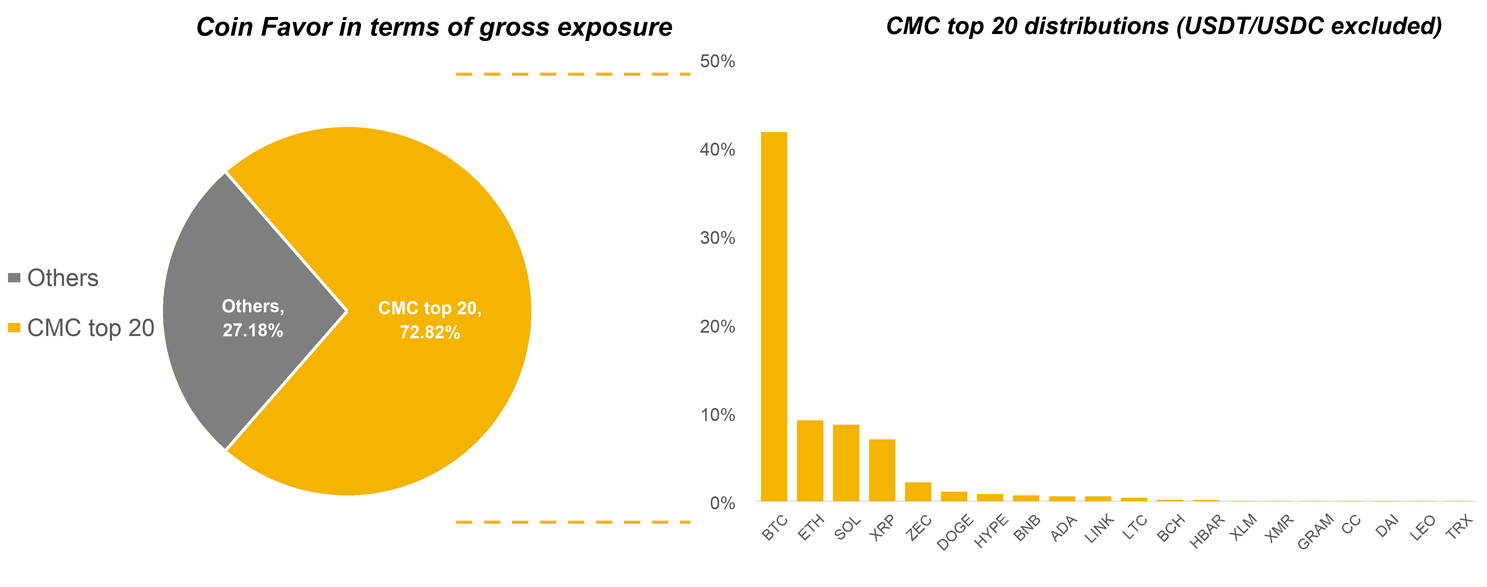
We aggregated daily position snapshots provided by participating trading teams over two monthly reporting periods: August 1 to September 1 and September 1 to October 1, 2026, with each period measured at a 00:00 UTC cut-off. Absolute USD exposure was consolidated by underlying asset to assess the allocation between CMC top-20 assets and other coins, as well as the concentration and diversification of each strategy’s coin exposure.
Overall, large-cap coins (CMC top 20) accounted for the majority of gross exposure in both August and September, although their share declined modestly in September. Among large-cap coins, BTC remained the largest exposure in our sample of participating teams, followed by ETH, XRP and SOL.
2026-08 | Coin distribution | directional
2026-09 | Coin distribution | directional
Note:
-
USD exposure = Delta * Underlying Price
-
See Index formula for full methodology and calculations.
To assess the dispersion across coins, we defined the aggregation degree β (ranging from 0 to 1). When β is closer to 1, it indicates that the investment is more concentrated in a few coins, while when β is closer to 0, it indicates that the investment is more diversified.
The aggregation degree, β, declined from 0.25 in August to 0.20 in September 2026, indicating a reduction in coin-level concentration. Exposure nevertheless remained more concentrated than in the Delta Neutral and Market Neutral samples across both months.
2026-08 | Coin exposure treemap | directional
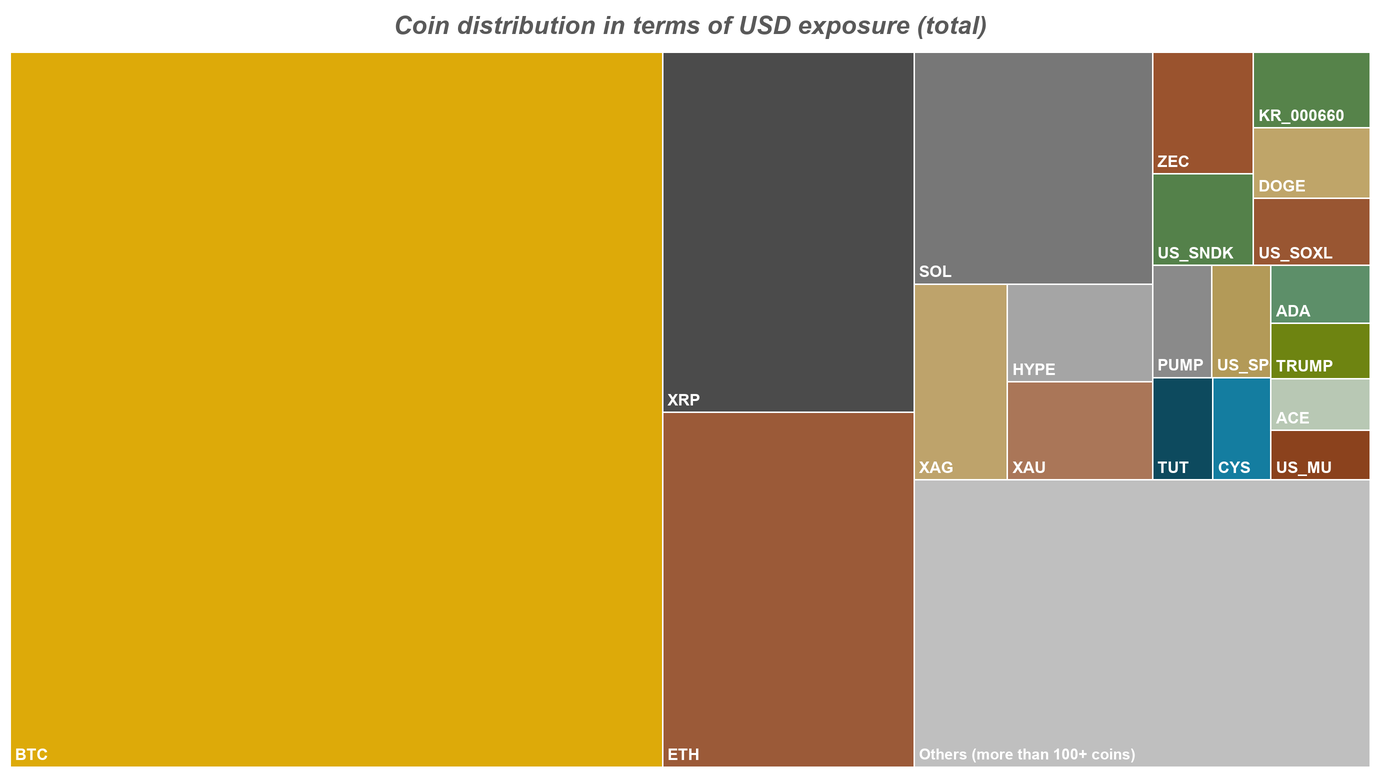
2026-09 | Coin exposure treemap | directional
The combined AUM of the participating teams exceeds $10 billion. We plan to expand the sample across more teams and regions to improve its representativeness and diversity.
Authored by Quinn Hu & Gloria Yao from 1Token, using data from the 1ndex platform and detailed data kindly provided by 8 participating trading teams.
Reference
Data Sources
Index performance and constituent-level observations were sourced from the 1ndex platform (https://1ndex.1token.tech/). Detailed trading data provided by participating teams supported the analysis of strategy characteristics, return composition, and coin-level exposure. Monthly index returns are measured from 00:00 UTC on the first day of each reporting month to 00:00 UTC on the first day of the following month, with annualized index returns calculated on a simple 365-day basis.
Acknowledgements
We thank the following eight trading teams for their collaboration and contribution of detailed trading data to this report:
Binquant
-
Delta Neutral and Directional
-
Founded in 2018, Binquant focuses on quantitative development and asset management in the digital asset market and is now one of the largest digital asset managers. The main strategies include market-neutral arbitrage, CTA, high frequency, and DeFi. Main clients include hedge funds, VC funds, large financial institutions, family offices, and exchanges for asset accretion.
DSG
-
Market Neutral and Directional
-
DSG Tech is a quantitative investment firm specializing in systematic trading across digital assets. The firm applies a multi-strategy approach spanning trend-following CTA, cross-sectional long-short relative value, high-frequency market maker and arbitrage, with a focus on liquid markets and efficient execution. Its investment process is grounded in rigorous empirical research, disciplined risk controls, and continuous refinement of models and infrastructure, with the objective of producing uncorrelated and repeatable returns over time.
Grandline
-
Delta Neutral and Market Neutral
-
GrandLine Technologies is a systematic multi-strategy trading firm established in 2018. Grandline specializes in deploying mid-frequency market-neutral strategies across major digital assets on both centralized and decentralized exchanges. With decades of expertise in quantitative portfolio management, the team is recognized for its exceptional research and risk management process, earning accolades from esteemed institutions like Hedgeweek and HFM.
Ladder Research
-
Delta Neutral
-
Ladder Research is a quantitative trading firm founded in 2022, focused on delta-neutral arbitrage strategies across markets. The core team has been active in the industry since 2018, with deep experience in exchange microstructure, execution, and risk management.
-
Ladder Research operates under a risk-first philosophy, aiming to deliver stable and scalable returns through disciplined execution and long-term iteration.
JZL
-
Delta Neutral
-
JZL Capital, specializing in Spot-Perpetual Arbitrage, is a top-tier quantitative team in Asia providing stable return performance and achieving over $200 million in AUM. The core team comprises members passionate about academic research and actively expanding its global client base by providing unparalleled quantitative trading solutions.
Pythagoras
-
Delta Neutral, Market Neutral and Directional
-
Established in 2014, Pythagoras manages a suite of crypto funds based on quantitative modeling. As one of the longest-running crypto hedge funds, it is known for delivering outstanding returns in both bearish and bullish market cycles. Using systematic, non-discretionary, and automated trading strategies, Pythagoras specializes in market-neutral and dollar-neutral strategies to consistently outperform the crypto market.
Tackzone
-
Delta Neutral
-
Tackzone Research is a quantitative research and strategy management fund focused on the digital asset market. We are committed to delivering stable and sustainable return solutions for investors through systematic strategies, rigorous risk controls, and efficient execution.
-
With long-term expertise in crypto derivatives and arbitrage, the team conducts quantitative research across funding rates, spread structures, liquidity conditions, and market microstructure, and has built an automated trading system spanning multiple exchanges and diverse strategy types.
-
We have established a full end-to-end closed loop covering strategy R&D, backtesting and evaluation, live trading operations, and risk management, ensuring disciplined implementation and continuous improvement across the entire investment lifecycle.
ZenX
-
Delta Neutral
-
ZenX was founded in 2019 and is headquartered in Hong Kong. ZenX is an innovative and established crypto trading firm with a focus on cutting-edge technology, data-driven solutions, and algorithmic modeling. We aim to build long-term relationships with clients by offering tailor-made services with professional trading expertise.
Collaboration teams for this study primarily come from Asia. In the future, we hope to expand the diversity of our sample to include teams across various regions around the world. If you'd like to be part of our benchmark study, please feel free to contact our partnership manager at joey.shi@1tokentech.com.
About 1Token
1Token (https://1token.tech/) is a SOC2 Compliant software for institutional Crypto Portfolio, Risk, Operations, Accounting and Lending Management, named Hedgeweek's 2024 "Portfolio Management Solution of the Year", serving 80+ top-tier institutional clients in the crypto industry, including SMA Allocators, Multi-Strategies Trading Funds, DMA Prime Brokers, Asset Managers, Lending Institutions, Fund Admins & Auditors across the US, EU, and APAC, collectively managing over $20 billion in assets.
For general inquiries like authorization requests of the report, product demo, or general collaboration opportunities, please email service@1token.trade.
Disclaimer
The information contained in this report is provided by 1Token for general informational purposes only and does not constitute professional advice. While every effort has been made to ensure the accuracy of the information, no warranty or representation, express or implied, is made regarding its completeness or reliability. The contents of this report reflect the views and opinions of the author(s) as of the date of publication, and may be subject to change without notice.
The reader should independently verify any information or conclusions presented herein before making decisions based on the report. 1Token and any affiliated parties are not responsible for any actions taken or not taken as a result of reading this report.
This report may contain forward-looking statements, estimates, and projections based on current expectations. These statements are subject to risks and uncertainties that could cause actual results to differ materially from those anticipated. 1Token assumes no obligation to update or revise any forward-looking statements.
Comments ()